





Speak with a licensed insurance agent

1-888-891-0229

Is Hospital Indemnity Insurance Worth It for Pregnancy? How to Decide

Reviewed by Russell Noga, Licensed Insurance Agent — Last updated October 28, 2026

Hospital indemnity insurance is often worth it for pregnancy if you enroll before you become pregnant, the plan covers childbirth and your health plan leaves you with a high deductible or coinsurance. It is usually not worth it if you are already pregnant, since many plans won’t pay for that delivery.

Having a baby costs more than most families expect, even with good health insurance. KFF found that people who give birth pay an average of $2,854 more out of pocket than people who don’t. A hospital indemnity plan can send you cash after the delivery stay to help cover that gap.

But the value depends on timing, plan rules and your own costs. This page gives you a clear way to decide. If you want the mechanics first, read how hospital indemnity insurance works for pregnancy.
Compare Hospital Indemnity Plans for Pregnancy

What Having a Baby Really Costs

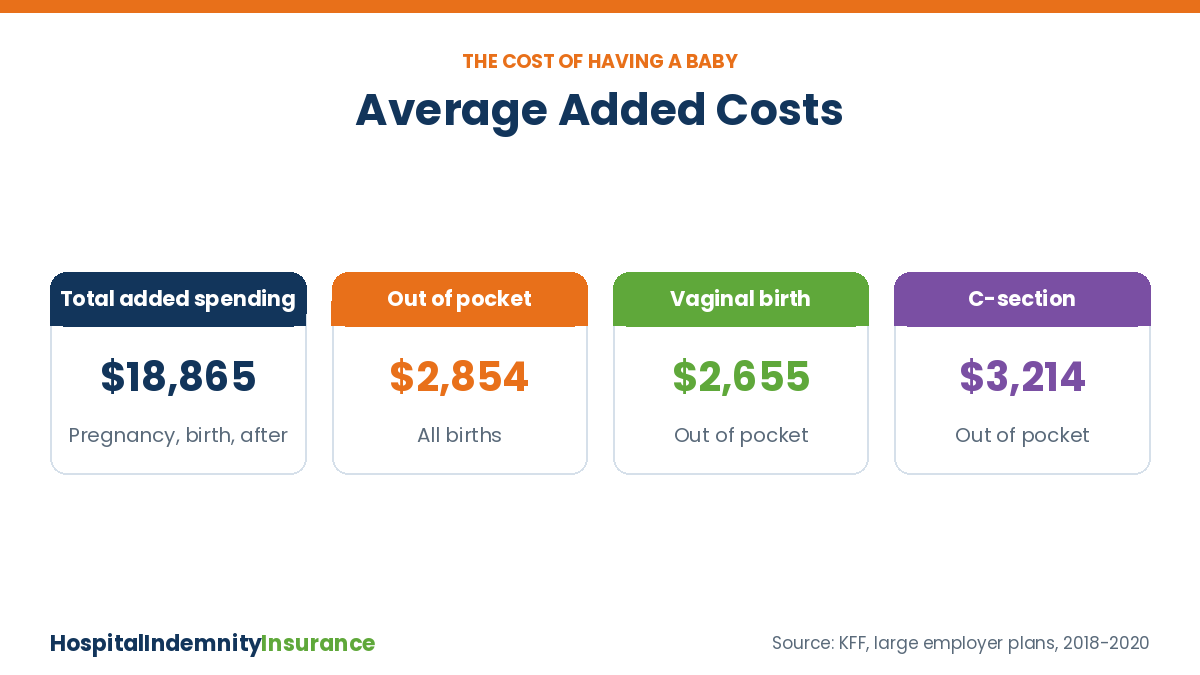
Is hospital indemnity insurance worth it for pregnancy: average added costs of giving birth

KFF studied claims from large employer health plans and compared people who gave birth with similar people who didn’t. The extra costs were large, and part of them landed on families.

Measure Average amount
Added health spending for pregnancy, birth and after $18,865
Added out-of-pocket cost, all births $2,854
Added out-of-pocket cost, vaginal birth $2,655
Added out-of-pocket cost, C-section $3,214

Source: KFF analysis of large employer plan claims, 2018-2020. Costs on high-deductible and Marketplace plans can be higher.

Your own share depends on your coverage. On a high-deductible plan, a single delivery can use up most or all of your deductible. On a Marketplace plan, maternity and newborn care are covered as essential health benefits, but deductibles and coinsurance still apply. If you have Medicaid, pregnancy care usually comes with little or no cost sharing, so a hospital indemnity plan is rarely needed.

Important: Hospital indemnity is a limited-benefit plan that pays fixed cash amounts. It is NOT health insurance, does not cover prenatal care, does not replace maternity coverage and does not meet ACA minimum essential coverage.

Hospital Indemnity Quotes

Call a Licensed Agent Now

Compare hospital indemnity plans from several insurance companies in one call. Any age.

☎ 1-888-891-0229

No obligation to enroll

When Hospital Indemnity Is Worth It for Pregnancy

You’re planning, not yet pregnant. Enrolling ahead of time means any waiting period is likely over by your due date.

You have a high deductible. A delivery can use up most or all of it. A cash payout helps cover what you owe.

You’ll lose income. Self-employed parents and workers without paid leave can use the cash for rent and groceries.

Your pregnancy is higher risk. Extra hospital days, a C-section or a NICU stay can raise payouts on many plans.

For higher-risk situations, see hospital indemnity insurance for high-risk pregnancy. Plans can also cover a spouse and children, so one policy can help the whole family after the baby arrives.

When It's Probably Not Worth It

You’re already pregnant. Many plans treat a pregnancy that started before coverage as pre-existing and won’t pay for that delivery.

Your waiting period won’t end in time. Guardian, for example, says its group plans don’t pay for a birth in the first 9 months of coverage.

Your costs are already low. If your health plan has a low out-of-pocket limit, the premium may outweigh the payout.

The plan excludes childbirth. Some policies only pay for complications, not a routine delivery.

Real-world warning: In a case reported in January 2025, a Colorado couple enrolled in an employer hospital indemnity plan while already pregnant. The insurer denied the birth claim, treating the pregnancy as a pre-existing condition. Read the definitions before you enroll.

Learn more in hospital indemnity insurance pregnancy waiting period.

Run the Numbers on Your Own Plan

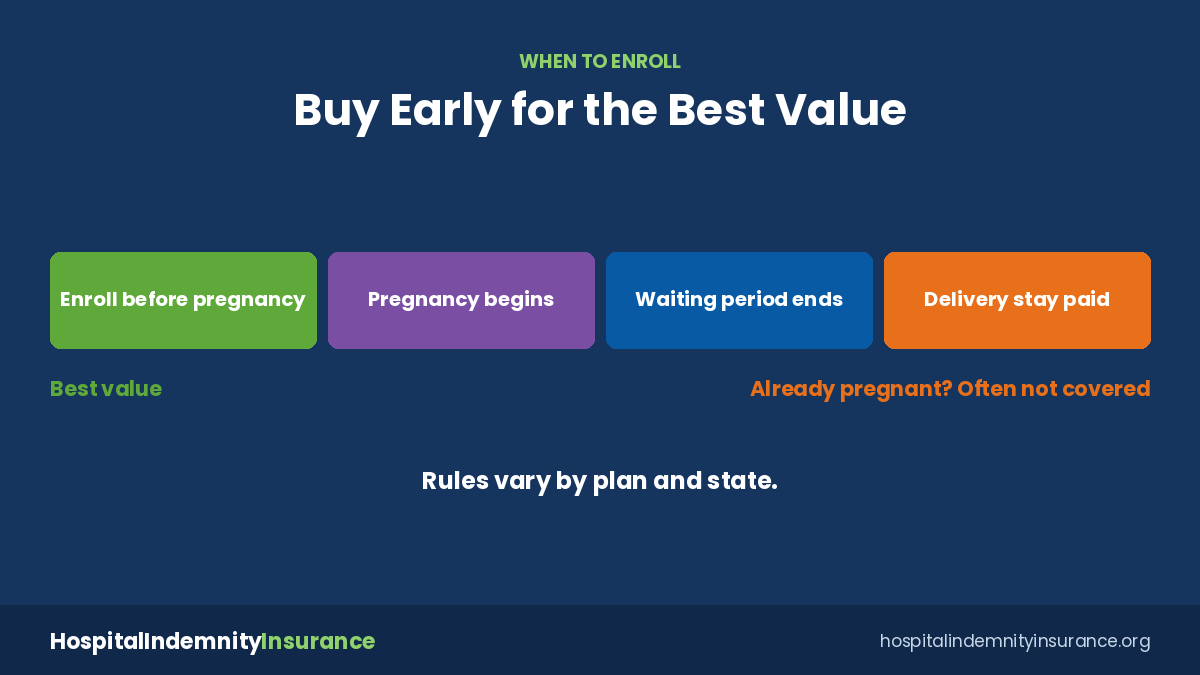
Is hospital indemnity insurance worth it for pregnancy: when to enroll timeline

The simplest test is to compare what you’d pay in premiums before your due date with what the plan would pay for a delivery.

1

Find your delivery cost. Check your deductible, hospital coinsurance and out-of-pocket maximum. Your share is often close to the deductible or the limit.

2

Find the plan’s payout. Add the admission benefit, the daily benefit times the expected days (often 2 for a vaginal birth, more for a C-section) and any newborn benefit.

3

Total your premiums. Multiply the monthly premium by the months you’ll pay before and after the birth.

4

Compare. If the payout is well above your premiums and the plan covers your delivery, it is likely worth it.

Don’t forget the costs your health plan never sees. Unpaid parental leave, a longer recovery after a C-section, travel to a NICU and child care for older kids can add up to more than the hospital bill. Because hospital indemnity pays cash to you, it can help with all of these, which is a big part of its value for new parents.

Plan feature to check Why it matters for pregnancy
Admission benefit Usually the biggest part of a delivery payout
Daily benefit and day limit Adds up for C-sections and complications
Newborn or NICU benefits Pays more if your baby needs extra care
Waiting period or pre-existing rule Decides whether this delivery is covered at all

Benefits vary by insurer, plan and state. Always read the outline of coverage.

See Pregnancy-Friendly Hospital Plans Near You

Timing Is Everything

Most of the value of hospital indemnity for pregnancy comes from buying early. Workplace plans usually let you sign up only during open enrollment or after a qualifying life event, so a family plan often means enrolling a year or more before you need it.

1

Before trying to conceive. The best time to enroll.

2

At open enrollment. Workplace plans often have simple approval and payroll deductions.

3

Once coverage starts. Note any waiting period end date on your calendar.

4

Before your due date. Confirm what the plan pays and how to add your newborn.

Already expecting? Read can you get hospital indemnity insurance if already pregnant before you buy anything.

Our Take

For many growing families, hospital indemnity is a reasonable, low-stress way to soften the cost of a delivery. It is not a must-have, and it is never a substitute for health insurance with maternity coverage, which ACA-compliant plans include as an essential health benefit.

Worth a look. You’ll enroll before pregnancy, the plan covers childbirth in writing and your deductible is high.

Skip it or wait. You’re already pregnant, the plan excludes routine delivery or your costs are low.

Still on the fence? Our guide to whether you should get hospital indemnity insurance for pregnancy walks through common family situations.

Bottom Line

Hospital indemnity insurance is worth it for pregnancy when you enroll before you’re pregnant, the plan clearly covers childbirth and your health plan leaves you with real out-of-pocket costs. If you’re already pregnant or your costs are low, it usually isn’t worth the premium. Either way, it adds to your health insurance and never replaces it.

Related: how much the hospital bill for having a baby is See median birth costs, what is on the bill and how to lower your share.

Get Free Hospital Indemnity Insurance Quotes

Is Hospital Indemnity Insurance Worth It for Pregnancy — Frequently Asked Questions

➤ Is hospital indemnity insurance worth it for pregnancy?

It often is if you enroll before you’re pregnant, the plan covers childbirth and you face a high deductible or coinsurance. It’s usually not worth it if you’re already pregnant.

➤ How much does having a baby cost out of pocket?

KFF found people who give birth pay about $2,854 more out of pocket on average, including about $2,655 for a vaginal birth and $3,214 for a C-section, on large employer plans.

➤ Will hospital indemnity pay if I’m already pregnant?

Often not for that delivery. Many plans treat an existing pregnancy as pre-existing or have waiting periods. Complications may be handled differently, so check the policy.

➤ How long is the pregnancy waiting period?

It varies. Some workplace plans have none, while Guardian says its group plans don’t pay for a birth in the first 9 months of coverage.

➤ Does hospital indemnity cover prenatal care?

Usually not. Most plans pay for hospital stays, not routine prenatal visits, ultrasounds or lab work.

➤ Is it worth it for a planned C-section?

It can be, since a C-section usually means a longer stay and more daily benefits. The waiting period and pre-existing rules still apply.

➤ Can I use the payout for anything?

Yes. The cash goes to you and can pay a deductible, unpaid leave, child care, baby supplies or household bills.

➤ Does hospital indemnity replace maternity insurance?

No. It is a limited-benefit plan that pays fixed cash amounts. It doesn’t pay your medical bills and doesn’t meet ACA minimum essential coverage.

Hospital Indemnity Quotes

Call a Licensed Agent Now

Compare hospital indemnity plans from several insurance companies in one call. Any age.

☎ 1-888-891-0229

No obligation to enroll

Find & Compare Plans Online

Speak with a licensed insurance agent

1-888-891-0229

ZRN Health & Financial Services, LLC, a Texas limited liability company