





Speak with a licensed insurance agent

1-888-891-0229

Aetna Supplemental Hospital Indemnity Insurance: How It Stacks on Your Main Coverage

Reviewed by Russell Noga, Licensed Insurance Agent — Last updated November 18, 2026

Aetna supplemental hospital indemnity insurance is a fixed-cash policy from Aetna, a CVS Health company, that pays you set dollar amounts for a covered hospital stay on top of whatever your main health coverage pays. Individuals buy it as Hospital Indemnity Flex, issued by Continental Life Insurance Company of Brentwood, Tennessee, through licensed agents, while workers get it at work through employer plans insured by Aetna Life Insurance Company.

2027 by the Numbers

A (Excellent)

AM Best rating for Aetna Life and Continental Life, affirmed June 2026

$1,750

2027 minimum deductible for an HSA-qualified plan, self-only (IRS Rev. Proc. 2026-24)

$1,736

2026 Medicare Part A hospital deductible per benefit period (CMS)

The word supplemental is doing real work in this product’s name. An Aetna hospital indemnity policy is built to ride along with another plan, not to stand alone. Your primary coverage pays the hospital under its own rules, while the Aetna policy pays a preset amount to you, and neither payment shrinks the other.

This page is about that layering: which primary plans it sits on, which Aetna company actually stands behind the policy, the two ways to get one, and the jobs it was never designed to do. For the benefit-by-benefit list, see what Aetna hospital indemnity covers. It is a limited-benefit plan, not health insurance, and it does not count as ACA minimum essential coverage.
Compare Aetna and Other Hospital Cash Plans in Your State

The Coverage Gaps Aetna Hospital Cash Is Built to Sit On

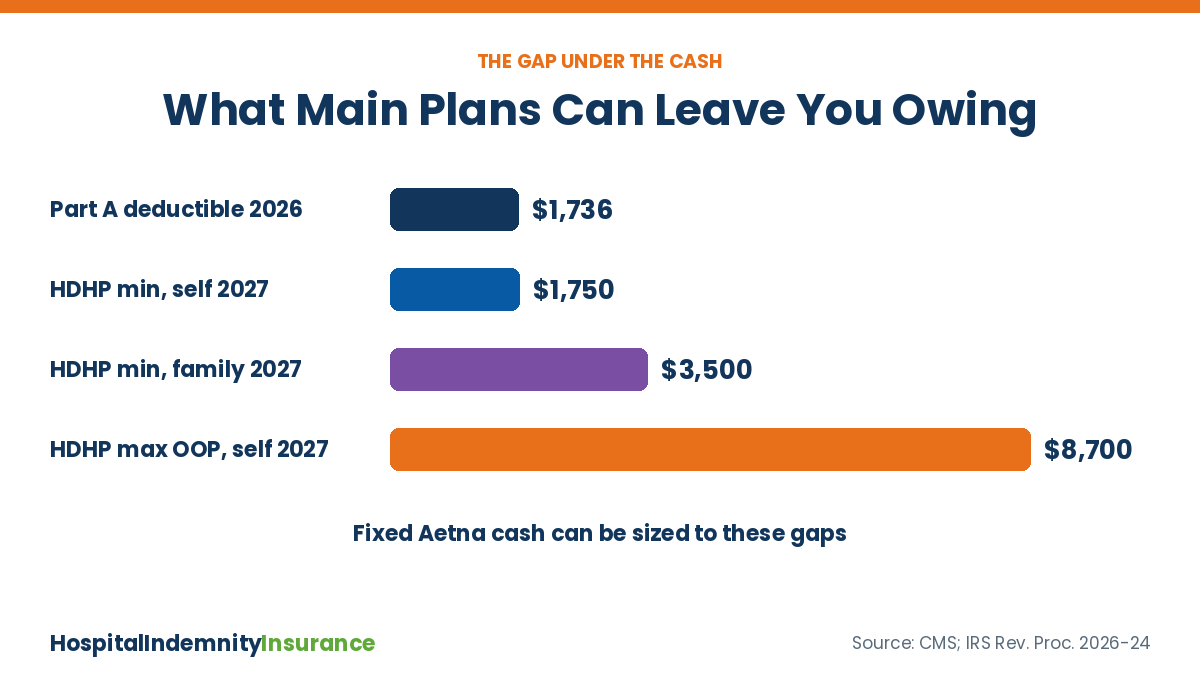
Aetna supplemental hospital indemnity insurance sits on coverage gaps: HDHP deductibles and Medicare Part A deductible

Every major plan leaves you something to pay when you are admitted: a deductible, coinsurance or a per-day copay. The size and shape of that gap decides how much an Aetna supplemental policy can help.

Your main coverage What a hospital stay can leave you owing Where Aetna hospital cash fits Check before you stack
High-deductible plan with an HSA 2027 minimum deductible of $1,750 self-only or $3,500 family, with out-of-pocket limits up to $8,700 or $17,400 A lump sum can cover the deductible so HSA dollars stay invested Aetna’s Brookhaven summary states its plan is HSA compatible; confirm your own summary says the same
Employer PPO or HMO Deductible plus coinsurance, up to the plan’s out-of-pocket maximum Cash is paid in addition to any other health coverage you have Group amounts differ from one employer to the next
ACA Marketplace plan Deductibles and copays by metal level Aetna cash can still sit on a plan from another insurer Aetna left the ACA exchanges after 2025, so the Marketplace plan itself will not be Aetna
Original Medicare without Medigap $1,736 Part A deductible per benefit period in 2026, then daily coinsurance on long stays Admission cash can absorb the Part A deductible The policy is not a Medicare Supplement and does not fill Medicare gaps automatically
Medicare Advantage Per-day inpatient copays set by each plan Aetna markets Hospital Indemnity Flex to work alongside Medicare Advantage plans Match daily benefit days to the copay days in your plan

Compiled by HospitalIndemnityInsurance.org from IRS Rev. Proc. 2026-24, CMS 2026 figures and Aetna documents, November 2026.

Stacking note: A fixed-indemnity payment is the same whether the hospital bill is $5,000 or $50,000. It fits best where your primary plan leaves a known, fixed dollar gap, such as a deductible or a daily copay.

Hospital Indemnity Quotes

Call a Licensed Agent Now

Compare hospital indemnity plans from several insurance companies in one call. Any age.

☎ 1-888-891-0229

No obligation to enroll

Which Aetna Company Is Behind Your Policy

Aetna is the brand, but the policy form names a specific insurance company, and that company depends on how you bought it. This matters when you read a claim letter, check a rating, or look up a filing with your state insurance department.

How you get it Product name Issuing company AM Best rating
Through an employer Aetna hospital indemnity (group, often listed under Aetna Voluntary Plans) Aetna Life Insurance Company A (Excellent), stable
On your own, through an agent Hospital Indemnity Flex Continental Life Insurance Company of Brentwood, Tennessee A (Excellent), stable
Sister company in the same group Shown on some Aetna individual product charts American Continental Insurance Company A (Excellent), stable

Issuers from Aetna’s Hospital Indemnity Flex page and employer summaries; ratings from AM Best, June 2026.

All three sat inside CVS Health’s Aetna group with the same AM Best rating and stable outlook in 2026. Your benefit amounts and state rules come from the form the issuing company filed, so read the company name on the outline of coverage, not just the logo.

Aetna's Other Supplemental Lines and How They Fit Together

Hospital indemnity is one piece of a small Aetna supplemental family. Each piece pays on a different trigger, so they overlap less than people expect.

Accident plan. Pays set amounts after a covered accidental injury and the care that follows it, whether or not you are admitted.

Critical illness plan. Pays a lump sum when you are diagnosed with a listed condition, even before any hospital stay begins.

Hospital indemnity plan. Pays when you are admitted, whatever the cause, illness or injury. It is the one that tracks the hospital stay itself.

Riders on the individual plan. Hospital Indemnity Flex can add riders such as ER or ambulance, doctor visits, skilled nursing days and a lump-sum cancer benefit, some of which ask health questions.

At work, Aetna’s claims flyer groups its accident, critical illness and hospital indemnity plans under one portal, MyAetnaSupplemental.com. It asks for an itemized bill or a UB-04 billing form and says an Explanation of Benefits alone is not accepted. One employer’s flyer lists a yearly screening payment of $100 under critical illness and $50 under hospital indemnity.

Two Ways to Buy Aetna Supplemental Insurance

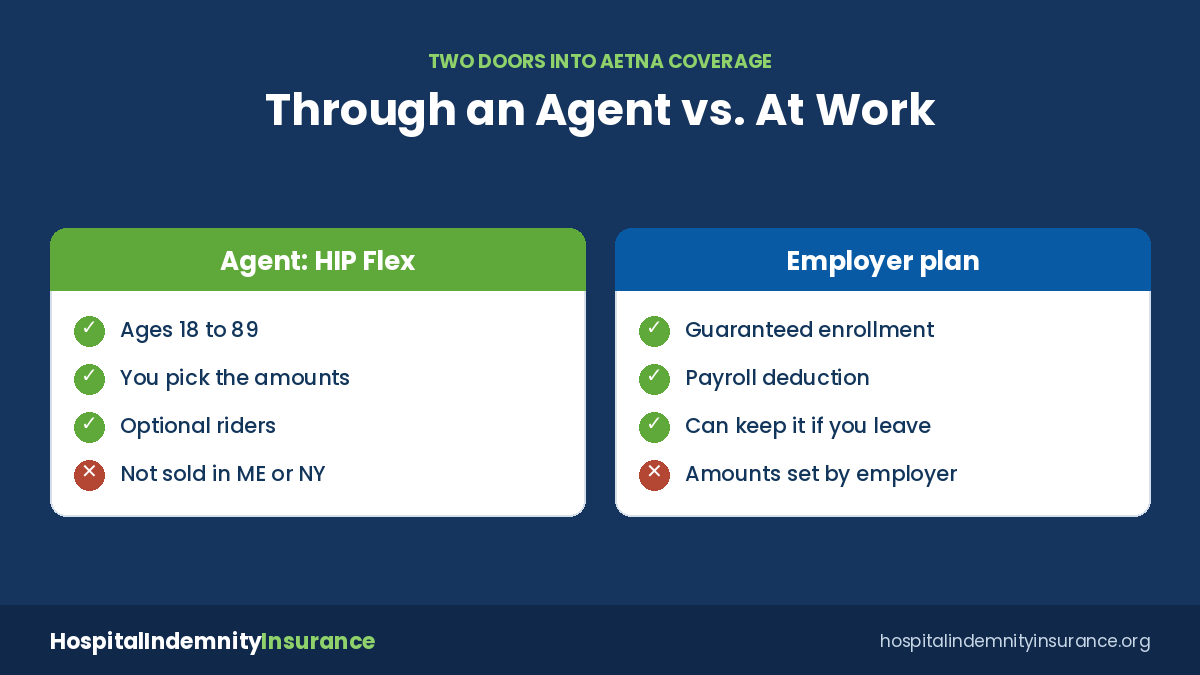
Two ways to buy Aetna supplemental hospital indemnity insurance: through an agent or through an employer

There is no public Aetna supplemental sign-up page. You come in through one of two doors, and each sets its own rules for who can enroll and who picks the amounts.

The agent door. Hospital Indemnity Flex is sold by licensed agents who are contracted and appointed with Aetna. Aetna lists issue ages of 18 to 89, ages 18 to 64 in California, and no sales in Maine or New York. You choose the admission or daily amount yourself.

The workplace door. Your employer picks the plan design and you enroll during its benefits window, usually with payroll deduction. Aetna’s Brookhaven summary describes enrollment as guaranteed, with no evidence of insurability.

Leaving a job. That same summary says you can take the plan with you by paying premiums directly if you lose eligibility, which keeps the supplement in place while you change primary coverage.

Workplace rules, payroll costs and enrollment timing are covered in depth on Aetna voluntary hospital indemnity insurance. For the individual plan’s amounts and riders, see Aetna Hospital Indemnity Flex.

See Which Supplemental Hospital Plans Are Sold in Your ZIP Code

What Aetna Supplemental Hospital Indemnity Will Not Do

Aetna’s employer summaries spell out the limits in capital letters, and they are worth reading first.

It will not replace your health plan. Aetna’s Brookhaven summary calls the plan a supplement to health insurance and not a substitute for major medical coverage. Its federal disclosure reads: fixed indemnity policy, NOT health insurance.

It will not satisfy a coverage mandate. The same summary states it does not count as minimum essential coverage under the Affordable Care Act, so it cannot meet a state rule that requires that coverage.

It will not act as a Medicare Supplement. It pays fixed amounts per event; it does not pick up a set share of Medicare-approved charges the way a Medigap plan does.

It will not grow with the bill. The payout is tied to the event and the schedule you chose, not to what the hospital charged or what your health plan allowed.

Mandate states: Massachusetts, New Jersey, California, Rhode Island and the District of Columbia have their own health coverage requirements. A hospital indemnity policy does not meet them, and Aetna’s employer summaries carry a separate Massachusetts notice for that reason.

A Layering Checklist Before You Add Aetna Coverage

1

Write down your primary plan’s hospital cost. Note the deductible, any daily inpatient copay and the out-of-pocket maximum. That is the gap the Aetna cash is meant to cover.

2

Find out which door is open. Check your employer’s benefits guide first. If Aetna is not offered at work, ask a licensed agent whether Hospital Indemnity Flex is sold in your state and at your age.

3

Size the benefit to the gap. A lump-sum admission benefit lines up with a deductible. A daily benefit lines up with per-day copays, which is common on Medicare Advantage.

4

Confirm the HSA wording. If you fund an HSA, look for the HSA compatible statement in your Aetna summary. Our guide on whether hospital indemnity is HSA eligible explains the federal rule.

5

Keep the main plan active. The supplement pays fixed amounts only. Without primary coverage, you could owe nearly the whole hospital bill.

On Medicare, the details of pairing Hospital Indemnity Flex with Medicare Advantage or Medigap are on the Aetna Medicare hospital indemnity plan page.

Bottom Line

Aetna supplemental hospital indemnity insurance works best as a top layer: a fixed cash payment sized to the deductible or daily copay your main plan leaves behind. Know which Aetna company issues your form, which door you are buying through, and keep your primary coverage in force underneath it.

Get Free Quotes on Supplemental Hospital Coverage

Aetna Supplemental Hospital Indemnity Insurance — Frequently Asked Questions

➤ What does supplemental mean on an Aetna hospital indemnity policy?

It means the policy pays in addition to your main coverage rather than in place of it. Aetna’s employer summaries state benefits are paid in addition to any other health coverage you have, and that the plan is not a substitute for major medical.

➤ Do I need Aetna health insurance to buy Aetna supplemental coverage?

No. The cash pays regardless of who your primary insurer is. Only the workplace version requires that your employer offers it.

➤ Can Aetna hospital cash stack on a Marketplace plan from another insurer?

Yes. Aetna stopped selling ACA exchange plans after 2025, so a Marketplace plan today comes from a different company, but a separately bought Aetna indemnity policy can still pay on top of it.

➤ Does the Aetna payment count toward my health plan’s deductible?

Not by itself, because it is paid to you, not billed through your health plan. If you use the cash to pay the hospital, that payment counts toward your deductible like any other money you pay the provider.

➤ Which company name will be on my Aetna paperwork?

Workplace plans are insured by Aetna Life Insurance Company. Individual Hospital Indemnity Flex policies are issued by Continental Life Insurance Company of Brentwood, Tennessee.

➤ Does Aetna supplemental insurance meet a state coverage requirement?

No. Aetna’s summaries say the plan does not count as ACA minimum essential coverage, so it will not satisfy coverage mandates in places such as Massachusetts, New Jersey or California.

➤ Can the benefit be paid to the hospital instead of to me?

On Hospital Indemnity Flex, Aetna says benefits can go to the insured person or a designated medical provider. Otherwise the money is yours to direct.

➤ What other Aetna plans are offered alongside hospital indemnity at work?

Many employers pair it with Aetna accident and critical illness plans. All three are filed through MyAetnaSupplemental.com or the My Aetna Supplemental app.

Hospital Indemnity Quotes

Call a Licensed Agent Now

Compare hospital indemnity plans from several insurance companies in one call. Any age.

☎ 1-888-891-0229

No obligation to enroll

Find & Compare Plans Online

Speak with a licensed insurance agent

1-888-891-0229

ZRN Health & Financial Services, LLC, a Texas limited liability company