Speak with a licensed insurance agent

1-888-891-0229

Blue Cross Blue Shield Hospital Indemnity Insurance: Coverage, Benefits and Quotes

Reviewed by Russell Noga, Licensed Insurance Agent | Last updated October 15, 2026

Blue Cross Blue Shield hospital indemnity insurance pays you a fixed cash benefit after a covered hospital stay, on top of your health plan or Medicare. Plans, benefits and availability depend on your local Blue Cross and Blue Shield company.

Unlike major medical insurance, hospital indemnity insurance pays you directly, so you can use the money for deductibles, hospital copays, household bills, travel or anything else a hospital stay puts on your plate.

Before choosing a plan from Blue Cross Blue Shield, Unum, Sun Life or another insurer, look closely at the daily hospital benefit, admission payments, waiting periods, exclusions and how the policy works with the coverage you already have.

✔ Cash paid directly to you
✔ Works with Medicare and employer plans
✔ Free, no-obligation quotes

Key Takeaways

✔

Hospital indemnity insurance pays fixed cash benefits directly to you after covered hospital events.

✔

It supplements, not replaces, major medical insurance, Medicare or employer health coverage.

✔

Blue Cross Blue Shield plans are offered by independent local companies, so options vary by state.

✔

Cash benefits can help with deductibles, copays, lost income, transportation and household bills.

✔

Review benefit amounts, exclusions, waiting periods and pre-existing condition limits before you enroll.

Get Free Hospital Indemnity Insurance Quotes

How Blue Cross Blue Shield Hospital Indemnity Insurance Works

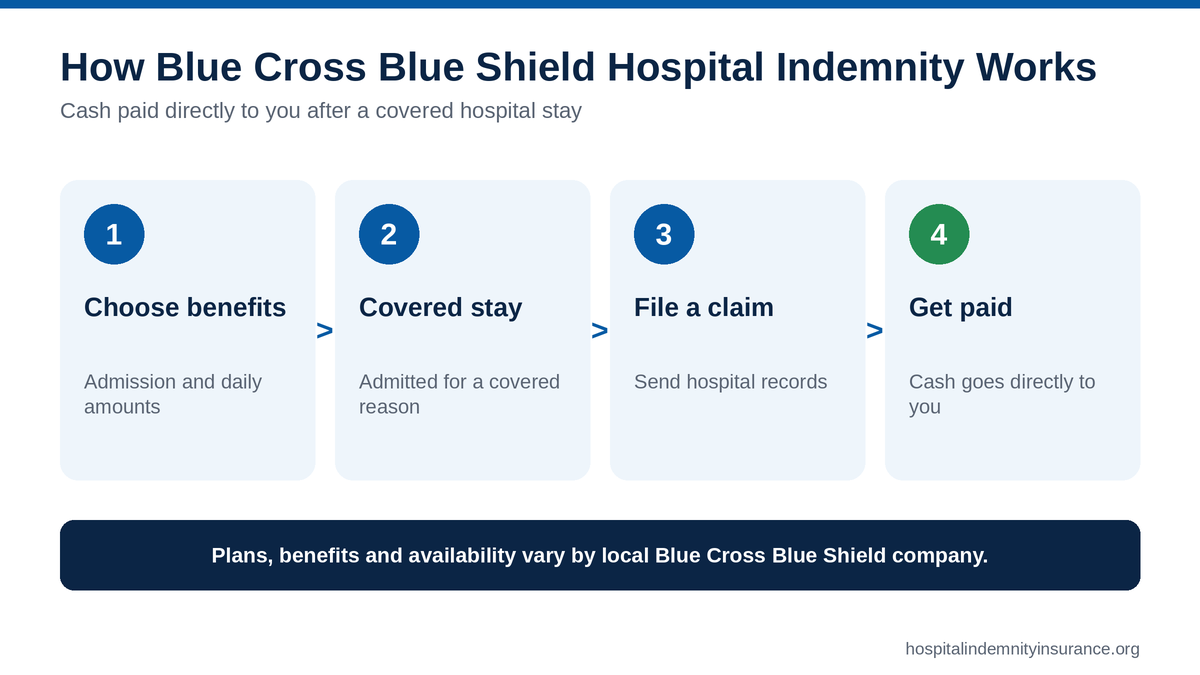
How Blue Cross Blue Shield hospital indemnity insurance works in four steps from choosing benefits to getting paid

Blue Cross Blue Shield hospital indemnity insurance is a supplemental policy that pays a set dollar amount when you are admitted to the hospital or receive other covered care. Traditional health insurance pays doctors, hospitals and pharmacies. A hospital indemnity policy pays you.

Step by Step

1

Choose your benefits. You pick the benefit amounts when you enroll, such as an admission benefit, a daily hospital benefit, or both.

2

Have a covered hospital stay. You are admitted to the hospital for a reason the policy covers.

3

File a claim. You send the insurer a claim form with hospital records showing your admission and discharge dates.

4

Get paid. The insurer pays the fixed benefit directly to you, no matter what your health plan or Medicare paid the hospital.

Real-world example: Blue Cross and Blue Shield of Kansas lists a Secure Hospital Indemnity Plan that pays cash directly to you when you are hospitalized, to help with costs your health insurance does not pay. Other Blue companies may offer different plans or none at all.

Why Benefits Vary by Blue Cross Blue Shield Company

Blue Cross Blue Shield is not one insurance company. It is a group of independent, locally operated companies, and each one designs and sells its own products in its own service area. That means a hospital indemnity plan in one state can look very different from a plan in another state, and some Blue companies may not offer one to individuals at all.

What Can Differ From State to State

✔

Whether a hospital indemnity plan is offered to individuals, Medicare members or only employer groups

✔

Admission and daily benefit amounts

✔

How many days per stay or per year the policy pays

✔

Optional benefits such as intensive care, outpatient surgery or ambulance coverage

✔

Waiting periods, pre-existing condition rules and exclusions

Read the plan documents: the Blue Cross Blue Shield name does not mean a uniform set of benefits. Always check the outline of coverage for the exact policy you are considering.

What Hospital Indemnity Benefits May Include

Depending on the plan and your state, hospital indemnity coverage may pay benefits for:

Benefits Some Plans May Include

✔

A lump-sum benefit when you are admitted to the hospital

✔

A daily benefit for each day of a covered inpatient stay

✔

Intensive care unit (ICU) stays

✔

Outpatient surgery or certain outpatient procedures

✔

Emergency room visits or ambulance transportation

Not all plans offer all benefits. The amount is set by the policy, so it is not tied to the hospital’s bill or to what your primary insurance pays.

Hospital Indemnity vs. Health Insurance

Hospital indemnity coverage and health insurance do two different jobs when a serious illness or injury interrupts your life:

Feature Health Insurance Hospital Indemnity Insurance
Primary role Pays for direct medical treatment costs Pays supplemental cash after a covered event
Who gets paid Doctors, hospitals and pharmacies You, directly
How benefits are set Network rules, deductibles, copays and coinsurance Fixed amounts set by the policy
How the money is used Covered medical services only Medical costs or everyday bills, your choice
Limits Plan’s covered services and networks Benefit schedules, waiting periods, exclusions and day caps

Health insurance can leave real out-of-pocket costs even when your care is covered. A hospital indemnity policy can help close that gap.

Compare Hospital Indemnity Plans in Your Area

Using Hospital Indemnity Insurance With Medicare

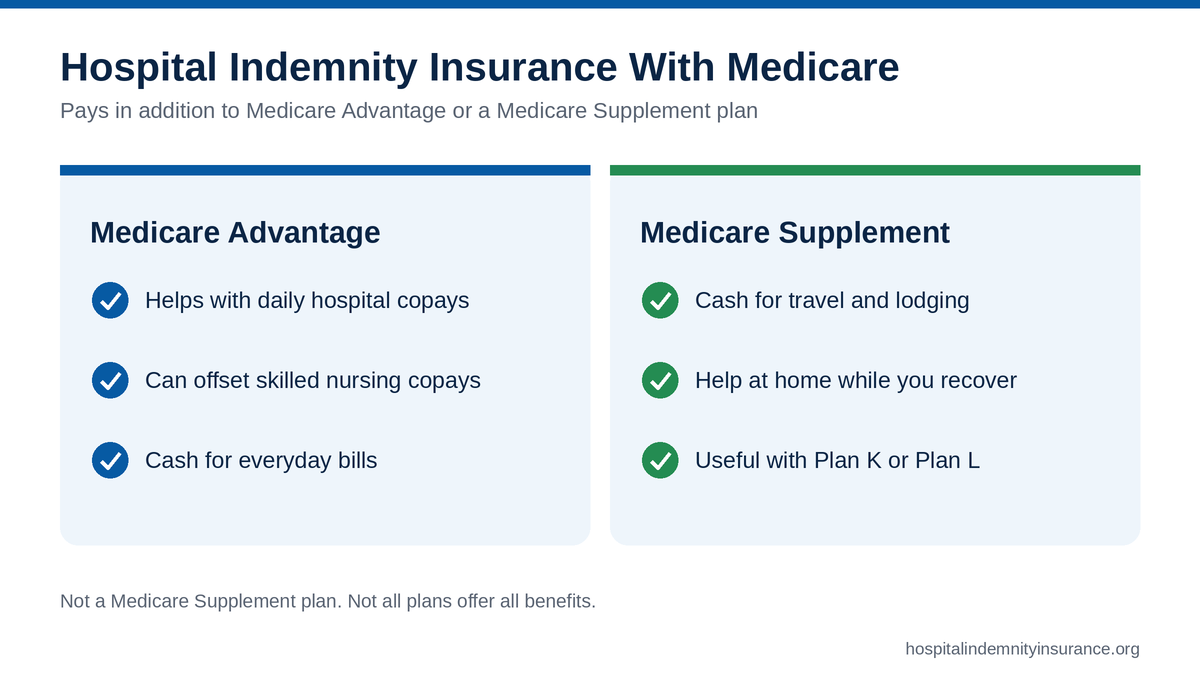
How hospital indemnity insurance works with Medicare Advantage and Medicare Supplement plans

Hospital indemnity insurance pays in addition to Original Medicare, Medicare Advantage or a Medicare Supplement plan. It is not a Medicare plan, so in most cases you can buy it any time of year, not just during Medicare enrollment periods.

Medicare Advantage Members

✔

Many plans charge a daily copay for the first several days of a hospital stay

✔

A daily benefit close to your plan’s copay can offset much of that cost

✔

Cash can also help with skilled nursing and ambulance copays

Medicare Supplement Members

✔

Most Medigap plans already cover the Part A hospital deductible

✔

Cash can still help with travel, home help and household bills

✔

May fit plans with more cost sharing, such as Plan K or Plan L

Keep in mind: hospital indemnity insurance is not Medicare Supplement insurance. It does not replace Medicare, Medicare Advantage or any other primary coverage.

Buying Through an Employer or on Your Own

You may be able to get hospital indemnity coverage as a workplace benefit or as an individual policy. Each route has trade-offs:

Through an Employer

✔

Offered as a voluntary benefit at many companies

✔

Premiums are often paid through payroll deduction

✔

Coverage may change or end if you leave the job

On Your Own

✔

You own the policy and choose the benefit amounts

✔

Coverage stays with you if you change jobs or retire

✔

You can compare plans from several insurers

If you are choosing through work, ask your benefits team which insurer issues the plan, what the benefits are and what happens to the coverage if you leave.

What to Check Before You Enroll

Plan Checklist

1

Benefit amounts. Check the admission benefit, the daily benefit and how many days the policy pays per stay and per year.

2

Covered events. Confirm what counts as a hospital admission and whether observation stays, ICU care or outpatient surgery are covered.

3

Waiting periods. Find out when benefits start and how pre-existing conditions are handled.

4

Exclusions. Read the list of conditions and situations the policy will not pay for.

5

Premium. Compare the monthly cost against the benefits. Our guide to hospital indemnity insurance cost explains what drives the price.

6

Claims process. Learn what documents you need and how quickly claims are paid.

Is Blue Cross Blue Shield Hospital Indemnity Insurance Worth It?

Hospital indemnity insurance can be worth considering if a hospital stay would strain your budget, even with good medical coverage. The value depends on how well your savings and current benefits could absorb an unexpected admission.

Often Makes Sense For

✔

Medicare Advantage members with daily hospital copays

✔

People with high-deductible health plans

✔

Families with limited paid leave or savings

✔

Anyone with a higher chance of a hospital stay

May Need Less Coverage If

✔

You have plenty of savings to absorb a hospital bill

✔

Your current plan has low hospital cost sharing

✔

The premium would strain your monthly budget

To see how Blue Cross Blue Shield compares with other insurers, read our comparison of top hospital indemnity insurance companies.

Bottom Line

The Bottom Line

Blue Cross Blue Shield hospital indemnity insurance can put cash in your hands when a hospital stay hits, but plans vary by local Blue company. Compare benefits, exclusions and premiums from several insurers before you choose.

Get Your Free Hospital Indemnity Quote

Frequently Asked Questions

➤ What is Blue Cross Blue Shield hospital indemnity insurance?

It is supplemental insurance that generally pays a fixed cash benefit directly to you after a covered hospital admission, inpatient stay or other qualifying event. Benefits, availability and rules vary by the local Blue Cross and Blue Shield company and the policy.

➤ Does every Blue Cross Blue Shield company sell hospital indemnity insurance?

No. Blue Cross Blue Shield coverage comes from independent, locally operated companies, and each one decides which supplemental products it offers. Some offer hospital indemnity plans to individuals, Medicare members or employer groups, while others may not offer one in your area.

➤ Is hospital indemnity insurance the same as regular health insurance?

No. Major medical insurance helps pay providers for covered health care, subject to deductibles, copays, coinsurance and network terms. Hospital indemnity coverage pays a preset amount to the policyholder and is meant to supplement, not replace, comprehensive health coverage.

➤ How can I use a hospital indemnity payment?

Because the payment is generally made directly to you, you can use it for medical cost sharing or for everyday expenses such as rent, groceries, transportation, parking, child care or household bills. The benefit does not automatically increase when hospital charges are higher.

➤ Does hospital indemnity insurance cover every hospital stay?

Not necessarily. Policies define what counts as a covered admission and may include exclusions, waiting periods, pre-existing condition limitations, benefit caps or limits on covered days. Review the policy’s definition of hospital confinement and its claim requirements before enrolling.

➤ Can I have hospital indemnity insurance with Medicare?

Yes. Hospital indemnity insurance can be held alongside Original Medicare, a Medicare Advantage plan or a Medicare Supplement plan. It is separate from Medicare Supplement insurance and does not take the place of Medicare or any other primary coverage.

➤ Is Blue Cross Blue Shield hospital indemnity insurance worth it?

It may be useful if a hospital stay would strain your budget because of daily hospital copays, a high deductible, limited savings or family expenses. Compare the premium with the admission and daily benefits, exclusions, waiting periods and your existing savings.

➤ Can I get hospital indemnity insurance through my employer?

Many employers offer hospital indemnity insurance as a voluntary benefit, sometimes through a Blue Cross Blue Shield company and sometimes through another insurer. Ask your benefits team what happens to the coverage if you leave the job, since portability rules vary by policy.

➤ How do I file a hospital indemnity claim?

Claim steps depend on the insurer and policy. You may need a claim form, hospital records, admission and discharge dates and proof of the covered service. Check your plan documents or contact your local Blue Cross and Blue Shield company for current instructions.

➤ How do I compare Blue Cross Blue Shield with other hospital indemnity plans?

Enter your ZIP code on this page to compare hospital indemnity plans available in your area. A licensed insurance agent can show you benefits and premiums from several insurers side by side so you can choose the best fit.
Have Questions?

Speak with a licensed insurance agent

1-888-891-0229

Find & Compare Plans Online

Speak with a licensed insurance agent

1-888-891-0229

ZRN Health & Financial Services, LLC, a Texas limited liability company