Speak with a licensed insurance agent

1-888-891-0229

Hospital Indemnity Insurance Low vs High Plans: Which Level Is Right for You?

Reviewed by Russell Noga, Licensed Insurance Agent | Last updated October 15, 2026

Low hospital indemnity plans cost less and pay smaller cash benefits. High plans cost more and pay larger benefits for the same covered hospital events. The right level depends on the costs you would face, your savings and your budget.

Most hospital indemnity insurance plans pay fixed amounts for admissions, hospital days and certain services, on top of Medicare or your health plan. Choosing between low and high options comes down to how much cash you want after a hospital stay and how much premium you are willing to pay for it.

Related reading: does hospital indemnity insurance cover ER visits and can you have more than one hospital indemnity insurance plan.

✔ Same structure, different amounts
✔ Works with Medicare Advantage
✔ Free, no-obligation quotes

Key Takeaways

✔

Hospital indemnity insurance pays fixed cash benefits and does not replace health insurance or Medicare.

✔

Low-benefit plans generally cost less. High-benefit plans pay more for covered hospital events.

✔

Low and high options usually cover the same events. The difference is the dollar amount.

✔

Match the benefit to real costs, such as your Medicare Advantage daily hospital copay.

✔

Check observation-stay rules, waiting periods, exclusions and benefit limits on every plan.

Get Free Hospital Indemnity Insurance Quotes

Low vs. High Plans: The Core Difference

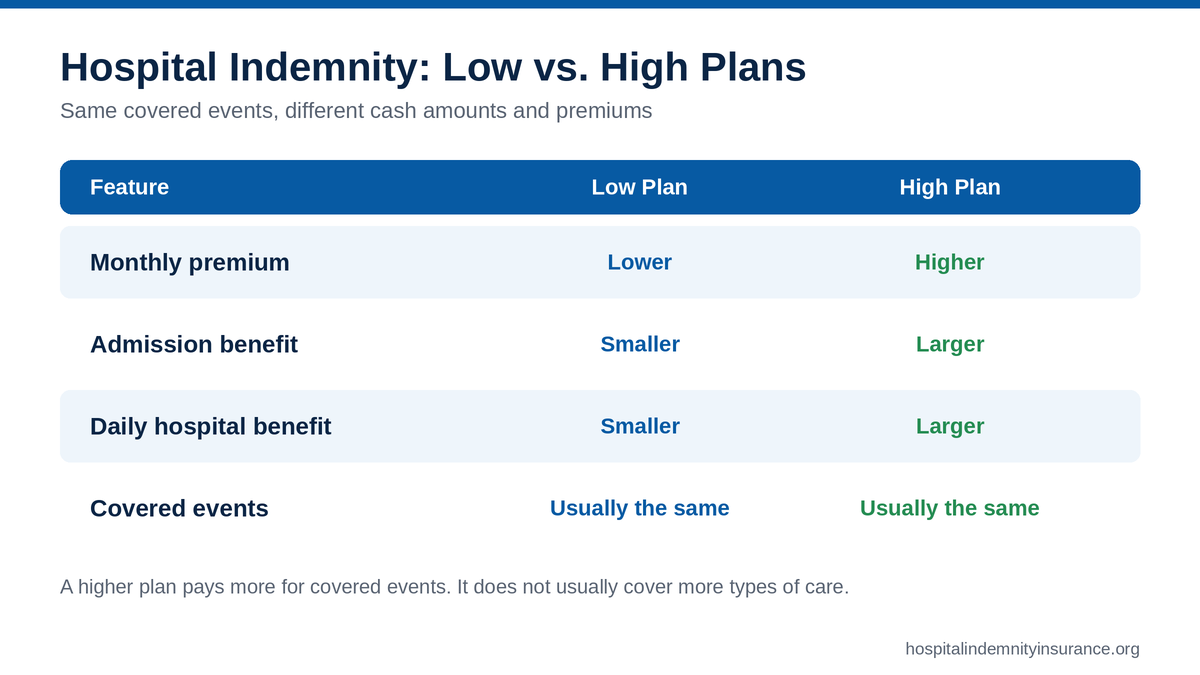
Hospital indemnity insurance low vs high plans compared by premium, admission benefit and daily benefit

Low and high plan options from the same insurer usually follow the same benefit structure. What changes is the dollar amount attached to each covered event and the premium you pay.

Feature Low Plan High Plan
Monthly premium Lower Higher
Admission benefit Smaller lump sum Larger lump sum
Daily hospital benefit Smaller daily amount Larger daily amount
Covered events Usually the same Usually the same
Best fit Tighter budgets, strong savings or low hospital cost sharing Higher hospital copays, limited savings or more financial risk

Key point: a higher plan does not usually cover more types of care. It pays more money when a covered event happens.

What Hospital Indemnity Insurance Does Not Replace

Hospital indemnity insurance is supplemental coverage. Your health plan or Medicare pays doctors and hospitals for covered care, subject to deductibles, copays and network rules. A hospital indemnity plan pays a set amount to you when a covered hospital stay happens.

Good to know: no matter which level you choose, hospital indemnity insurance does not negotiate medical bills, guarantee access to providers or replace the broad protection of health insurance. It adds a cash cushion on top.

Benefits to Compare Between Plan Levels

Compare Each Benefit

1

Admission benefit. A lump sum paid when a covered inpatient stay begins. Check whether it pays once per stay or is limited per year.

2

Daily hospital benefit. Paid for each covered day in the hospital, up to a stated maximum number of days.

3

ICU benefit. Some plans pay a higher daily rate for intensive care. Confirm whether ICU days also count toward the regular day limit.

4

Outpatient benefits. Some plans pay fixed amounts for emergency treatment, outpatient surgery or diagnostic tests.

5

Maximum limits. Compare the maximum days and dollars payable per stay, per year and over the life of the policy.

6

Premium. Compare the monthly cost of each level against the extra cash it would pay.

Compare Hospital Indemnity Plans in Your Area

Read the Payout Triggers

A bigger benefit does not help if the event never triggers a payment. Before choosing a level, check how the policy defines a covered event:

Payout Triggers to Check

✔

Whether the plan requires a formal inpatient admission

✔

Any minimum number of hours or an overnight stay

✔

How observation stays and same-day treatment are handled

✔

Which outpatient services qualify and what triggers payment

✔

Waiting periods and pre-existing condition rules

Why it matters: observation stays are common for people on Medicare. If a plan does not pay for observation status, a higher benefit level will not change that.

Premium vs. Potential Benefit

The right comparison is between the extra premium for a higher plan and the extra cash you would realistically receive. A higher daily benefit adds up quickly over a longer stay, but you pay the higher premium every month whether or not you use it.

Hypothetical example: a plan with a $200 daily benefit would pay $1,000 for a covered five-day stay, while a plan with a $100 daily benefit would pay $500 for the same stay. Actual benefit amounts and premiums vary by insurer, plan and state.

For a closer look at what drives the price, see our guide to hospital indemnity insurance cost.

Which Plan Level Fits You?

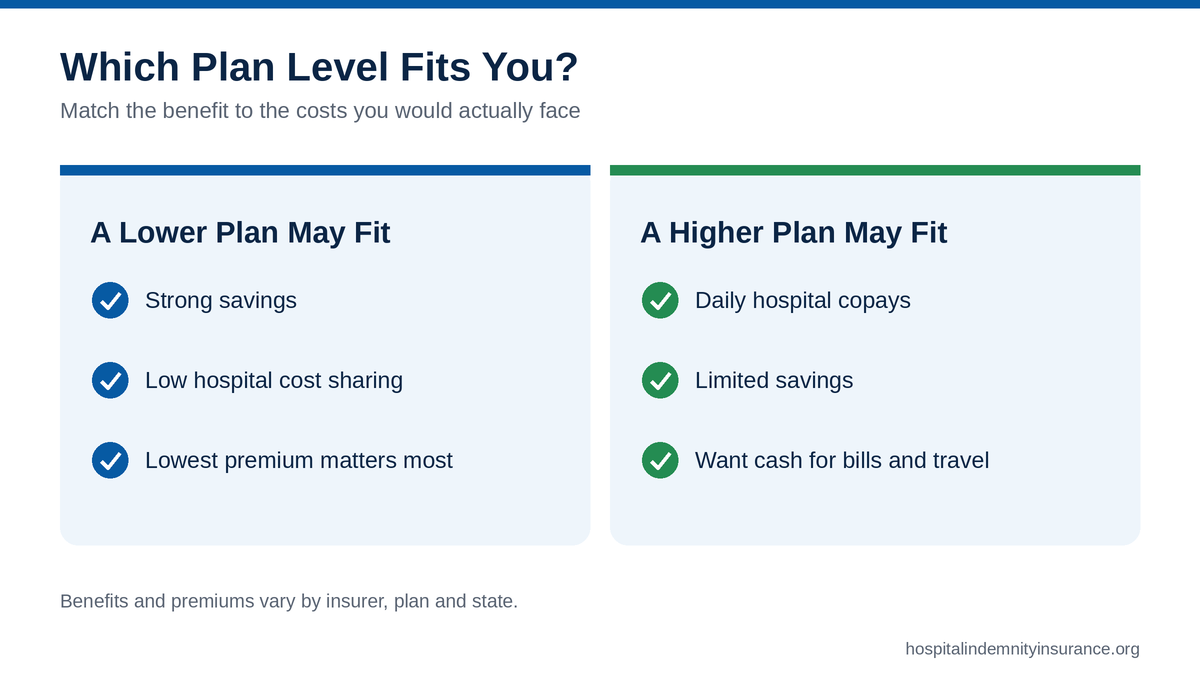
Which hospital indemnity plan level fits you: when a lower or higher plan may make sense

A Lower Plan May Fit If

✔

You have enough savings to cover most hospital costs

✔

Your current plan has low hospital cost sharing

✔

You want basic protection at the lowest premium

✔

You already have a Medigap plan that covers hospital costs

A Higher Plan May Fit If

✔

Your Medicare Advantage plan charges daily hospital copays

✔

A hospital stay would strain your budget or savings

✔

You have a chronic condition that raises the chance of a stay

✔

You want cash for lost income, travel or help at home

The goal is not to buy the most expensive plan. It is to choose the benefit level that closes the gap you are most worried about at a premium you can keep paying.

Matching Your Plan Level to Medicare

If you have a Medicare Advantage plan, your plan’s daily hospital copay is a natural starting point. Many Medicare Advantage plans charge a daily copay for the first several days of an inpatient stay. A hospital indemnity daily benefit close to that copay can offset much of the cost.

If you have Original Medicare with a Medicare Supplement plan that already covers the Part A deductible, a lower benefit level may be enough to cover travel, home help and household bills during recovery.

Illustrative Hospital Stay Scenarios

Scenario Possible Costs How a Cash Benefit Can Help
Unexpected surgery with a short admission Deductible or daily hospital copays, plus household bills Help cover cost sharing or ongoing expenses
Planned joint replacement with several days in the hospital Mobility aids, home support and recovery costs Help bridge recovery needs after discharge
Short stay after a serious illness Parking, meals for family and prescriptions after discharge Help with hospital-related and post-discharge expenses

Actual benefits depend on the policy terms and whether the stay qualifies. A higher plan level means more cash for each covered stay.

Fine Print to Check Before You Choose

Coverage Fine-Print Checklist

✔

How the policy defines hospital admission and confinement

✔

Maximum days paid per stay and per year

✔

Exclusions and pre-existing condition limitations

✔

Waiting periods before benefits begin

✔

Whether the policy is guaranteed renewable

✔

What documents are needed to file a claim

Bottom Line

The Bottom Line

Low and high hospital indemnity plans usually cover the same events. A high plan pays more cash for each covered stay at a higher premium. Match the benefit to the costs you would actually face, then compare quotes side by side.

Get Your Free Hospital Indemnity Quote

Frequently Asked Questions

➤ What is the difference between low and high hospital indemnity plans?

Low-benefit plans generally have lower premiums and smaller cash payouts. High-benefit plans usually cost more but pay larger amounts for admissions, daily hospital stays, ICU care or covered outpatient services. Both pay fixed amounts rather than a percentage of your hospital bill.

➤ Do low and high plans cover different things?

Usually not. Low and high options from the same insurer typically follow the same benefit structure. The main difference is the dollar amount attached to each covered event, and the premium you pay for it.

➤ How do I choose between a low and high hospital indemnity plan?

Start with the costs you would actually face, such as your Medicare Advantage daily hospital copay or your health plan deductible. Then compare those costs with your savings and budget, and choose the benefit level that closes the gap you are worried about at a premium you can keep paying.

➤ Is a high hospital indemnity plan worth the extra premium?

It can be if a hospital stay would create real financial strain, such as daily hospital copays, a high deductible, limited savings or lost income. If you have strong savings or low hospital cost sharing, a lower plan or no plan may make more sense.

➤ What is hospital indemnity insurance?

Hospital indemnity insurance is supplemental coverage that pays a fixed cash benefit when you have a covered hospital admission, inpatient stay, ICU stay or other listed event. The payment usually goes directly to you and can be used for medical or everyday expenses.

➤ Does hospital indemnity insurance replace health insurance?

No. Hospital indemnity coverage does not replace comprehensive health insurance or Medicare. A primary health plan pays for covered medical services, while hospital indemnity insurance provides preset cash payments for qualifying events.

➤ Does hospital indemnity insurance cover outpatient care?

Some policies include fixed benefits for specific outpatient services, such as emergency treatment, surgery or diagnostic testing. Coverage varies by plan and level, so review the qualifying procedures, limits and payout triggers.

➤ Will a hospital indemnity plan pay for observation status?

Not always. Many policies require an inpatient admission, and observation care or same-day treatment may not qualify. Check how the plan defines admission, any minimum-hour requirement and whether an overnight stay is required.

➤ Can I have more than one hospital indemnity plan?

In many cases, yes, because hospital indemnity policies generally pay regardless of other coverage. Before buying a second policy, compare the combined premium with simply choosing a higher benefit level on one plan.

➤ How do I compare low and high hospital indemnity plans?

Enter your ZIP code on this page to compare hospital indemnity plans available in your area. A licensed insurance agent can show you how different benefit levels change the premium so you can choose the right fit.
Have Questions?

Speak with a licensed insurance agent

1-888-891-0229

Find & Compare Plans Online

Speak with a licensed insurance agent

1-888-891-0229

ZRN Health & Financial Services, LLC, a Texas limited liability company