Speak with a licensed insurance agent

1-888-891-0229

Humana Hospital Indemnity Insurance: Coverage, Benefits and Quotes

Reviewed by Russell Noga, Licensed Insurance Agent | Last updated October 15, 2026

Humana hospital indemnity insurance pays you a fixed cash benefit after a covered hospital stay, on top of your health plan or Medicare. You decide how to spend the money, from deductibles and copays to everyday bills.

Humana hospital indemnity insurance is supplemental coverage, not a replacement for health insurance. This guide explains how it works, what benefits may be available, how it fits with Medicare, and what to compare before you enroll. Coverage, benefit amounts and claim rules vary by plan and state.

Comparing carriers? See our guides to Symetra hospital indemnity insurance and Lincoln Financial hospital indemnity insurance.

✔ Cash paid directly to you
✔ Works with Medicare and employer plans
✔ Free, no-obligation quotes
Key Takeaways

✔

Humana hospital indemnity insurance supplements primary coverage. It does not replace major medical insurance or Medicare.

✔

Covered hospital events trigger fixed cash benefits paid directly to you, not reimbursement of every medical bill.

✔

Cash can help with deductibles, copays, transportation, household bills, child care or lost work time.

✔

Check admission definitions, observation-status rules, waiting periods, exclusions and pre-existing condition limits.

✔

Plan availability, benefits and riders vary by state, so confirm the details where you live.

Get Free Hospital Indemnity Insurance Quotes

How Humana Hospital Indemnity Insurance Works

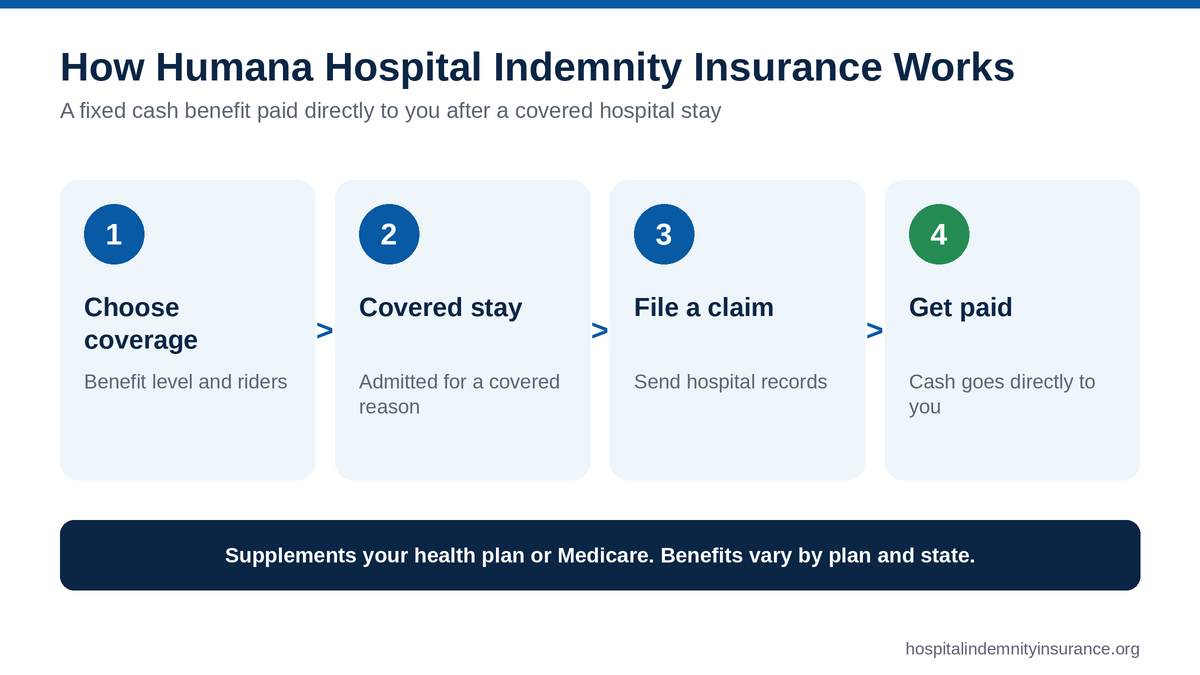
How Humana hospital indemnity insurance works in four steps from choosing coverage to getting paid

A hospital indemnity plan sits alongside your primary health coverage. Your health plan pays doctors, hospitals and pharmacies under its own network and cost-sharing rules. A hospital indemnity plan pays a set amount to you when a covered hospital stay happens.

Step by Step

1

Choose your coverage. You select the benefit level and any optional riders when you enroll, where available.

2

Have a covered hospital stay. You are admitted to the hospital for a reason the policy covers.

3

File a claim. You send a claim form with hospital records showing your admission and discharge dates.

4

Get paid. The insurer pays the fixed cash benefit to you, no matter what your health plan or Medicare paid.

From Humana’s plan materials: Humana’s workplace hospital indemnity summary describes a cash benefit paid during hospitalization that members can use however they want, with optional riders such as a first admission benefit and an intensive care benefit. Benefits and riders vary by state.

What Humana Hospital Indemnity Plans May Include

Depending on the plan, your state and the riders you choose, hospital indemnity coverage may pay benefits for:

Benefits Some Plans May Include

✔

A daily cash benefit for each day of a covered hospital confinement

✔

A lump-sum benefit for a first hospital admission

✔

Intensive care unit (ICU) stays

✔

Outpatient surgery or emergency treatment

✔

Ambulance transportation

Not all plans offer all benefits. The amount is set by the policy, so it is not tied to the hospital’s bill or to what your primary insurance pays.

Hospital Indemnity vs. Primary Health Insurance

Feature Primary Health Insurance Hospital Indemnity Insurance
Intended role Main coverage for medical care Supplemental coverage alongside your main plan
Who gets paid Doctors, facilities and pharmacies You, directly
How benefits are set Network and cost-sharing rules Fixed amounts for covered events
How the money is used Covered medical services only Medical costs or everyday bills, your choice
Scope Primary layer of medical coverage Does not replace comprehensive coverage

Health insurance can leave real out-of-pocket costs even when your care is covered. A hospital indemnity policy adds a cash cushion for the costs that come with a hospital stay.

Compare Hospital Indemnity Plans in Your Area

Using Hospital Indemnity Insurance With Medicare

Hospital indemnity insurance pays in addition to Original Medicare, Medicare Advantage or a Medicare Supplement plan. It is not a Medicare plan, so in most cases you can buy it any time of year, not just during Medicare enrollment periods.

Medicare Advantage Members

✔

Many plans charge a daily copay for the first several days of a hospital stay

✔

A daily benefit close to your plan’s copay can offset much of that cost

✔

Cash can also help with skilled nursing and ambulance copays

Medicare Supplement Members

✔

Most Medigap plans already cover the Part A hospital deductible

✔

Cash can still help with travel, home help and household bills

✔

May fit plans with more cost sharing, such as Plan K or Plan L

Know the difference: a Medicare Supplement plan pays according to Medicare’s rules for costs Original Medicare leaves behind. Hospital indemnity insurance pays a fixed cash amount to you after a covered hospital stay. They do different jobs and can be used together.

When a Hospital Visit May Not Qualify

Every hospital indemnity policy defines what counts as a covered hospitalization. Before you count on a benefit, check how the policy treats these situations:

Situations to Check

✔

Observation stays, when the hospital keeps you without formally admitting you

✔

Emergency room visits that do not lead to an inpatient admission

✔

Stays at certain facilities, such as rehab or nursing facilities

✔

Hospital stays tied to a pre-existing condition during the first months of coverage

✔

Conditions or treatments listed in the policy’s exclusions

Why it matters: observation stays are common for people on Medicare. If observation coverage matters to you, confirm it before you enroll.

What to Check Before You Enroll

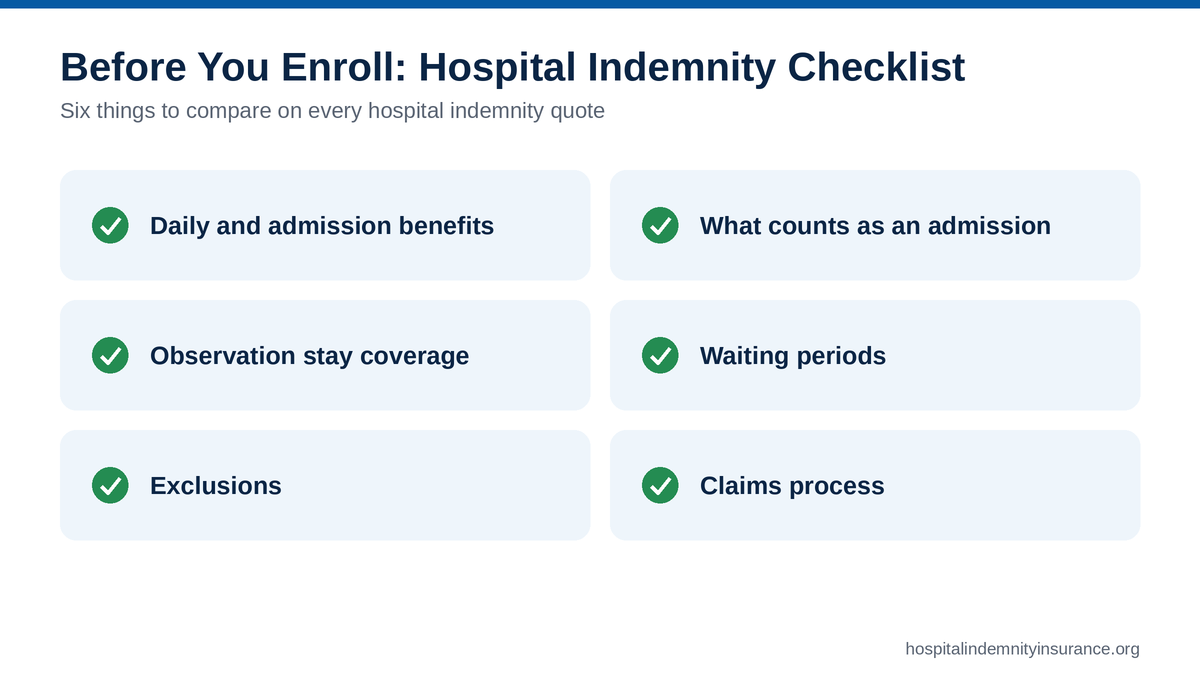
Checklist of what to compare before enrolling in a Humana hospital indemnity insurance plan

Plan Checklist

1

Benefit amounts. Check the daily benefit, any admission benefit and how many days the policy pays per stay.

2

Covered events. Confirm what counts as a hospital admission and whether observation stays, ICU care or outpatient surgery are covered.

3

Waiting periods. Find out when benefits start and how pre-existing conditions are handled in your state.

4

Exclusions. Read the list of conditions and situations the policy will not pay for.

5

Premium. Compare the monthly cost against the benefits. Our guide to hospital indemnity insurance cost explains what drives the price.

6

Claims process. Ask what documents are required, whether claims can be filed online and how long payment typically takes.

How to File a Hospital Indemnity Claim

Claim Steps

1

Keep your records. Save discharge papers, itemized bills and provider information from the hospital stay.

2

Get the claim form. Download it from the insurer or request it by phone or mail.

3

Submit your claim. Send the form with hospital documentation showing your admission and discharge dates.

4

Receive your benefit. Once the claim is approved, the cash benefit is paid directly to you.

Is Humana Hospital Indemnity Insurance Worth It?

Hospital indemnity insurance can be worth considering if a hospital stay would strain your budget, even with good medical coverage. The value depends on how well your savings and current benefits could absorb an unexpected admission.

Often Makes Sense For

✔

Medicare Advantage members with daily hospital copays

✔

People with high-deductible health plans

✔

Families with limited paid leave or savings

✔

Anyone with a higher chance of a hospital stay

May Need Less Coverage If

✔

You have plenty of savings to absorb a hospital