





Speak with a licensed insurance agent

1-888-891-0229

What Is Hospital Indemnity Insurance Through an Employer? A Plain-English Guide

Reviewed by Russell Noga, Licensed Insurance Agent — Last updated October 28, 2026

Hospital indemnity insurance through an employer is a voluntary workplace benefit that pays you fixed cash if you are admitted to the hospital. You usually pay the premium yourself through payroll deduction, and the money goes to you to use for deductibles, copays or everyday bills. It adds to your health plan; it does not replace it.

During open enrollment, many employers list hospital indemnity next to accident and critical illness coverage. It can look like just another checkbox, but it works very differently from your medical plan.

This guide explains what workplace hospital indemnity is, how it pays, what it typically costs, how taxes work and what to ask HR before you enroll. For a broader look at workplace coverage, see group hospital indemnity insurance.
Compare Hospital Indemnity Plans Outside Work

How Employer Hospital Indemnity Insurance Works

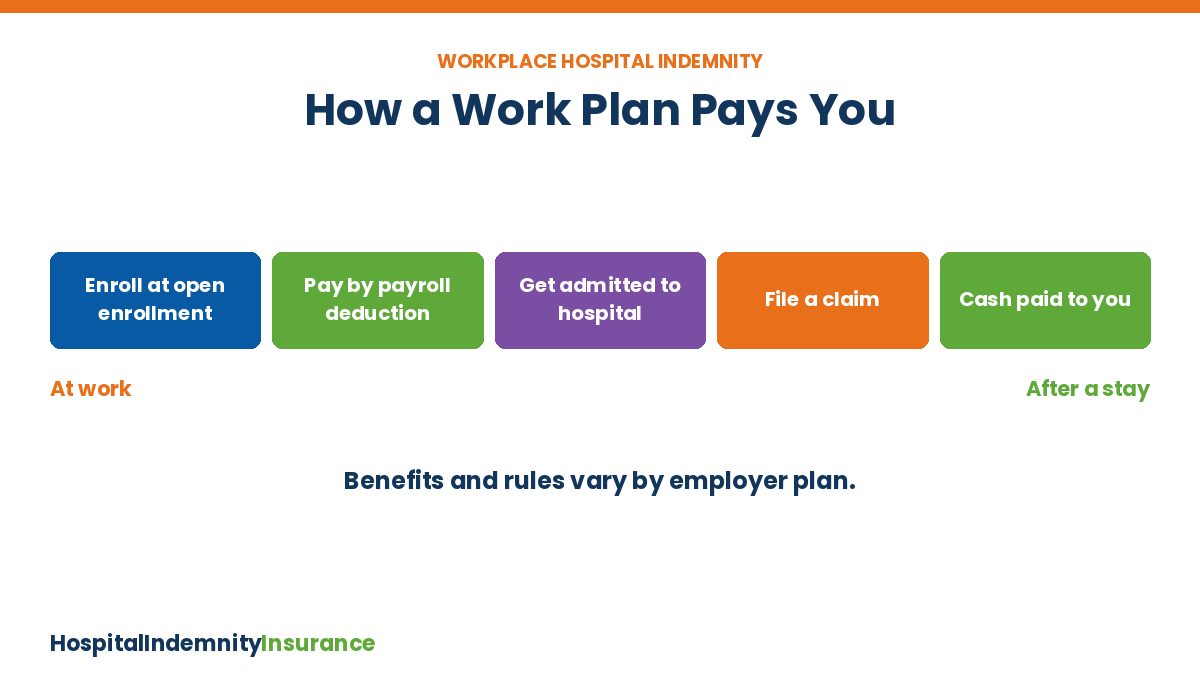
What is hospital indemnity insurance through an employer: enroll, pay by payroll, get admitted, get cash

Your employer holds a group policy with an insurer such as Aflac, MetLife, Cigna, Prudential or Mutual of Omaha. You choose whether to join and usually pay the full premium through payroll deduction, which is why it is often called a voluntary benefit.

Fixed cash per event. The plan pays a set amount for a covered hospital admission, each day you stay and often ICU days, no matter what the hospital bills.

Paid to you. Benefits go to you unless you assign them, so you can use the cash for anything.

Pays on top of your health plan. It pays regardless of what your medical plan covers, which helps with deductibles and coinsurance.

Here is a simple example. Say your health plan has a $3,000 deductible and you spend three nights in the hospital with pneumonia. Your medical plan pays the hospital after your deductible. Separately, a hospital indemnity plan paying $1,000 at admission and $200 a day would send you $1,600, which you could put toward that deductible, your rent or groceries while you recover.

Important: Hospital indemnity is a limited-benefit plan that pays fixed cash amounts. It is NOT health insurance, does not replace major medical coverage or Medicare and does not meet ACA minimum essential coverage.

Hospital Indemnity Quotes

Call a Licensed Agent Now

Compare hospital indemnity plans from several insurance companies in one call. Any age.

☎ 1-888-891-0229

No obligation to enroll

What a Workplace Plan Typically Pays

Each employer’s plan has its own benefit schedule. Here is a real example from a Prudential plan listed on a University of California, Riverside benefits rate sheet.

Benefit Amount Limit
Hospital admission $1,200 Up to 10 times a year
ICU admission $1,200 Up to 10 times a year
Hospital stay $200 a day Up to 30 days per stay
ICU stay $400 a day Up to 30 days per stay

Source: employer rate sheet. Your employer’s plan will differ.

That plan cost $16.19 a month for an employee and $42.49 for family coverage. Many group plans also add riders for ER visits, ambulance rides, outpatient surgery or wellness screenings. Learn more about voluntary hospital indemnity insurance.

When you compare your employer’s plan to others, look at the total a typical short stay would pay, not just one line of the schedule. A plan with a large admission benefit can pay more for a two- or three-day stay than a plan with a higher daily rate but no admission benefit.

Why People Choose Hospital Indemnity at Work

Working adults, young families and people with high-deductible health plans are the most common buyers at work, but anyone who would struggle to cover a surprise hospital bill can benefit.

Easier approval. Many group plans ask few or no health questions during your first enrollment window.

Payroll convenience. The premium comes out of your paycheck, so coverage is easy to keep.

Pregnancy planning. Some group plans have no pregnancy waiting period. Mutual of Omaha, for example, markets its group plan with none. See hospital indemnity for pregnancy.

High-deductible health plans. The cash can offset a large deductible. Read hospital indemnity for high-deductible plans.

Good to know: If you have an HSA-eligible health plan, ask HR whether the hospital indemnity plan is designed to work with an HSA. Some insurers offer HSA-compatible versions.

Taxes: Pre-Tax vs. After-Tax Premiums

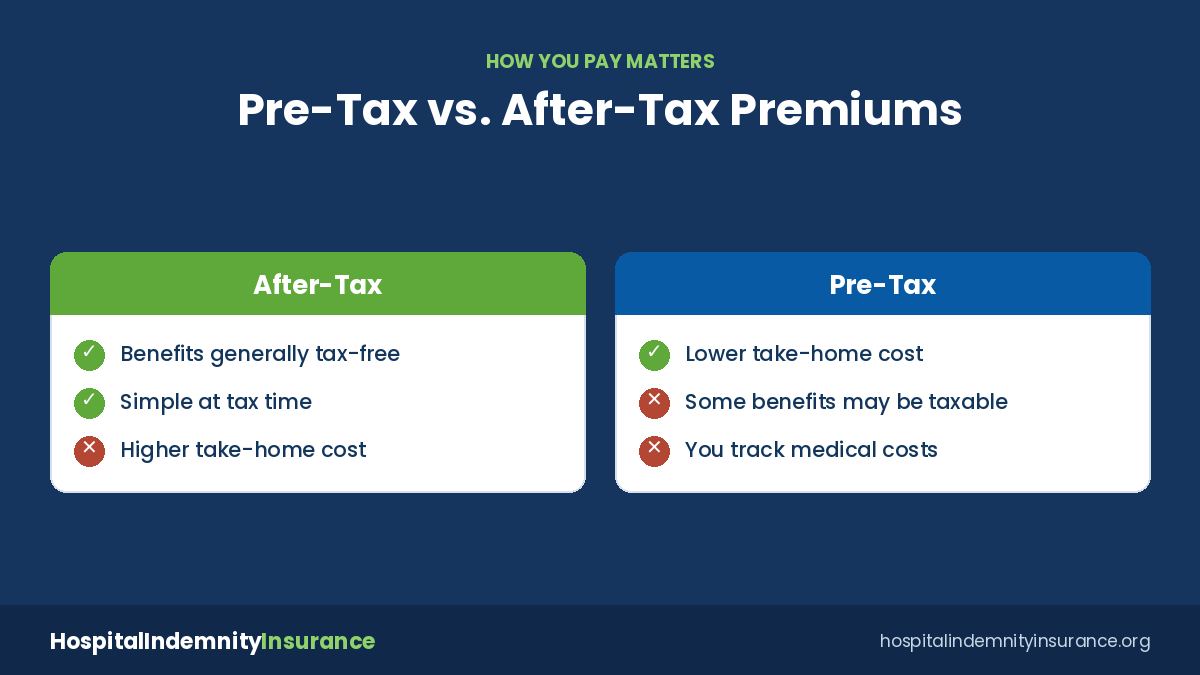
Hospital indemnity insurance through an employer pre-tax vs after-tax premiums compared

How you pay the premium can affect whether benefits are taxed. According to guidance summarized by Aflac, based on a 1969 IRS revenue ruling and a 2017 IRS memo:

How premiums are paid How benefits are generally treated
After-tax (from your take-home pay) Benefits are generally tax-free
Pre-tax, or paid by your employer Benefits are generally tax-free up to your unreimbursed medical expenses; any amount above that may be taxable income

Tax rules can change and depend on your situation. Ask HR or a tax professional.

Many employers let you choose, or set the plan up one way for everyone. If you are not sure, ask before you enroll.

Good to know: Your insurer or employer does not know your medical expenses, so if any part of a benefit is taxable, it is generally up to you to figure that out and report it on your tax return.

See Individual Hospital Plans in Your ZIP Code

Limits and What Happens If You Leave

Workplace plans are convenient, but they come with rules set by the group policy. These are the limits that most often surprise people at claim time or when they change jobs.

Pre-existing conditions. Some group plans limit benefits for conditions treated shortly before coverage starts.

Enrollment windows. You can usually join only at open enrollment or after a life event like marriage or a new baby.

Portability. Some plans let you keep coverage when you leave the job, often with age limits. One Cigna group plan, for example, required you to be under 70 to port coverage.

Observation stays. A night under observation may pay less than an admission, or nothing. Check the plan summary.

If your plan is not portable, compare it with an individual policy you would own yourself. Our guide to coordinating hospital indemnity with employer benefits explains how the pieces fit together.

Questions to Ask HR Before You Enroll

1

What does the plan pay? Ask for the benefit schedule: admission, daily, ICU and any riders.

2

Are there health questions? Find out if coverage is guaranteed during this enrollment window.

3

How does it handle pregnancy? Ask about waiting periods and whether a current pregnancy is covered.

4

Pre-tax or after-tax? Ask how premiums are deducted and how that affects benefit taxes.

5

Is it portable? Ask what happens to coverage and price if you leave the job.

6

How do claims work? Ask what paperwork is needed and how fast claims are paid.

Broker tip: If your employer’s plan is thin or not portable, a licensed agent can quote individual plans you can own for life, and you can often keep both, since hospital indemnity pays regardless of other coverage.

Bottom Line

Hospital indemnity insurance through an employer is a voluntary plan you pay for through payroll that sends you fixed cash for covered hospital stays. It is often easy to get and affordable, but it supplements your health plan rather than replacing it. Check the benefits, tax setup, pregnancy rules and portability before you enroll.

Get Free Hospital Indemnity Insurance Quotes

Hospital Indemnity Insurance Through an Employer — Frequently Asked Questions

➤ What is hospital indemnity insurance through an employer?

It is a voluntary group benefit that pays you fixed cash when you are admitted to the hospital. You usually pay the premium through payroll deduction.

➤ Does my employer pay for hospital indemnity?

Usually not. Most workplace hospital indemnity plans are employee-paid, though some employers contribute.

➤ Is employer hospital indemnity the same as health insurance?

No. It is a limited-benefit plan that pays fixed amounts. It does not replace your medical plan and does not meet ACA minimum essential coverage.

➤ Are hospital indemnity benefits taxable?

Benefits from after-tax premiums are generally tax-free. If premiums are pre-tax or employer-paid, benefits above your unreimbursed medical costs may be taxable. Ask a tax professional.

➤ Can I keep workplace hospital indemnity if I quit?

It depends. Some plans are portable, sometimes with age limits, while others end with your job.

➤ Does workplace hospital indemnity cover childbirth?

Many plans pay for a delivery stay. Some have no pregnancy waiting period, but others exclude a pregnancy that began before coverage. Check the plan summary.

➤ Is hospital indemnity through work worth it?

It often is if you have a high deductible, hospital copays or little emergency savings. Compare a year of premiums with what one stay would pay.

➤ Can I have both an employer plan and an individual plan?

Usually yes. Hospital indemnity pays regardless of other coverage, though some insurers limit total benefits. Read each policy.

Hospital Indemnity Quotes

Call a Licensed Agent Now

Compare hospital indemnity plans from several insurance companies in one call. Any age.

☎ 1-888-891-0229

No obligation to enroll

Find & Compare Plans Online

Speak with a licensed insurance agent

1-888-891-0229

ZRN Health & Financial Services, LLC, a Texas limited liability company