Speak with a licensed insurance agent

1-888-891-0229

Is Voluntary Hospital Indemnity Insurance Worth It? How to Decide at Open Enrollment

Reviewed by Russell Noga, Licensed Insurance Agent — Last updated October 28, 2026

Voluntary hospital indemnity insurance is often worth it if a hospital stay would leave you with a deductible or lost pay you could not easily cover. It is a workplace plan you pay for through payroll, and it sends you fixed cash after a covered stay. If you have strong savings and low out-of-pocket costs, the premium may do more good in your emergency fund.

Every open enrollment, many employers add a line for “hospital indemnity” next to accident and critical illness coverage. The word “voluntary” means you choose it and you usually pay the full premium through payroll deduction. The question is whether that small deduction buys real protection for your family.

This guide walks through the math, the tax rules and the fine print so you can decide in a few minutes. If you are new to these plans, start with our overview of voluntary hospital indemnity.
Compare Hospital Indemnity Plans in Your Area

What Voluntary Hospital Indemnity Insurance Is

Is voluntary hospital indemnity insurance worth it: average deductible and ACA out-of-pocket limits

Voluntary hospital indemnity is a group plan your employer makes available, but you pay for it, often with a small amount taken from each paycheck. When you or a covered family member is admitted to the hospital, the plan pays a set dollar amount, such as a lump sum for the admission and a daily amount for each day you stay. The cash goes to you, not to the hospital.

You pay, your employer arranges it. The employer picks the insurer and plan design. You decide whether to enroll and which coverage level to choose.

Group pricing and easy approval. Workplace plans are often offered with few or no health questions when you first become eligible.

Family tiers. Most plans let you cover yourself, your spouse, your children or the whole family.

Important: Hospital indemnity is a limited-benefit plan that pays fixed cash amounts. It is NOT health insurance, does not replace your medical plan and does not meet ACA minimum essential coverage.

Hospital Indemnity Quotes

Call a Licensed Agent Now

Compare hospital indemnity plans from several insurance companies in one call. Any age.

☎ 1-888-891-0229

No obligation to enroll

The Quick Math: Premium vs. Your Real Hospital Costs

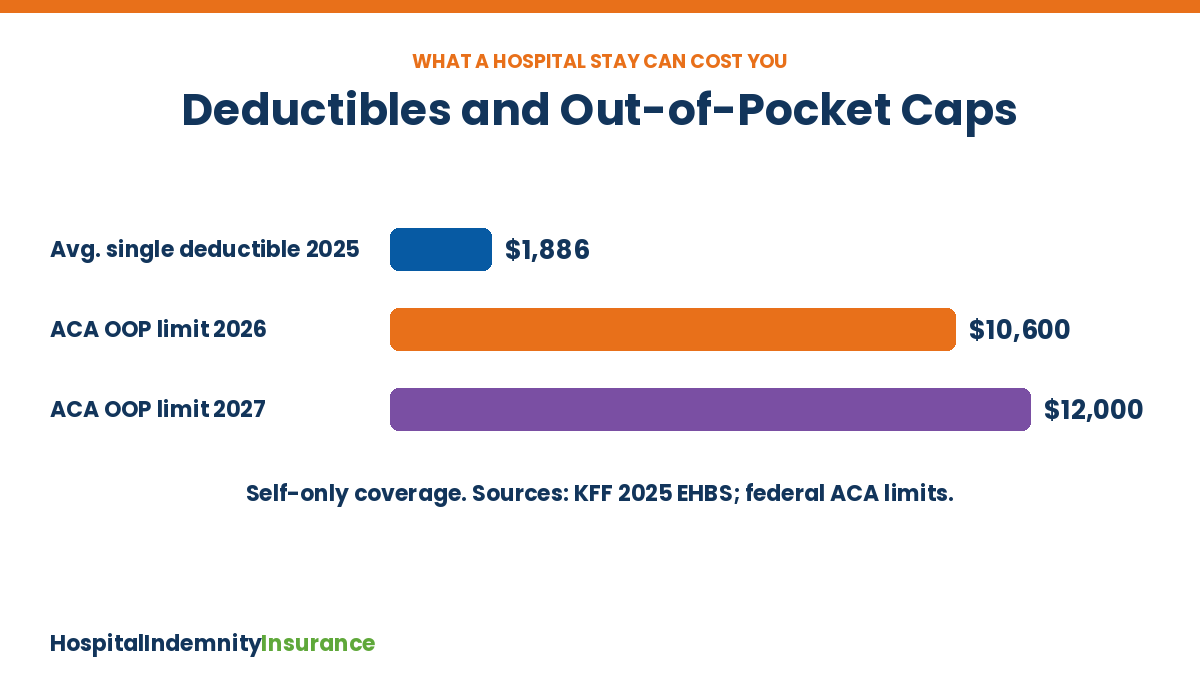
The value question comes down to two numbers: what you pay in a year and what one hospital stay would cost you out of pocket. Deductibles have been climbing. In KFF’s 2025 Employer Health Benefits Survey, the average deductible for single coverage was $1,886, and about one in three covered workers had a deductible of $2,000 or more.

Number to know Figure Why it matters
Average single deductible (workers with a deductible), 2025 $1,886 You usually pay this first when you are admitted
Workers with a single deductible of $2,000+ About 34% Higher deductibles make a cash benefit more useful
ACA out-of-pocket limit, self-only, 2026 $10,600 The most an in-network plan can make you pay in a year
ACA out-of-pocket limit, self-only, 2027 $12,000 The cap rises again next year

Sources: KFF 2025 Employer Health Benefits Survey; federal ACA cost-sharing limits. Your own plan may be lower.

Now compare that with a sample plan. For illustration only: a plan that costs $15 a month costs $180 a year. If it paid $1,000 for an admission and $200 a day, a three-day stay would pay $1,600. One stay could return many years of premiums, but if you are never admitted, you get nothing back, just like car or home insurance.

Rule of thumb: If writing a check for your full deductible tomorrow would be hard, the plan is more likely to be worth it. If you could pay it from savings without stress, it is a closer call.

Who Usually Gets the Most Value

Workers on a high-deductible plan. Cash from one stay can cover much of the deductible. See hospital indemnity for high-deductible plans.

Families planning a baby. Childbirth is often a hospital admission. Many plans pay for it, but some use waiting periods, so enroll before a pregnancy if you can.

People with little paid leave. The money is yours to use for rent, groceries or childcare while you recover.

Anyone with a chronic condition. If a hospital stay is more likely, the odds of collecting go up, though pre-existing condition rules may apply.

It tends to be less valuable if you have a large emergency fund, a low-deductible medical plan, generous paid sick leave and employer-paid disability coverage. In that case, you are already well protected against the costs this plan is built for.

Voluntary (Workplace) vs. Buying on Your Own

Is voluntary hospital indemnity insurance worth it compared with an individual plan

You can also buy hospital indemnity outside of work. Here is how the two compare.

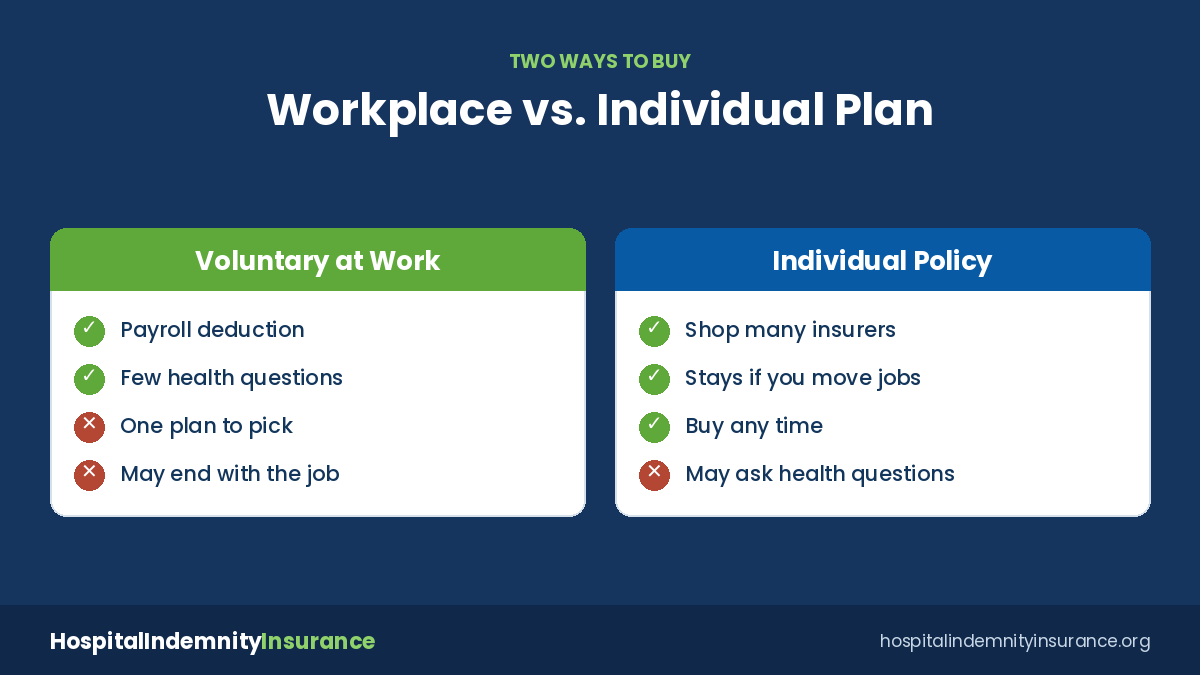
Feature Voluntary workplace plan Individual plan
How you pay Payroll deduction Directly to the insurer
Health questions Often few or none at first enrollment Varies; some plans ask, some have guaranteed-acceptance age windows
When you can join Open enrollment or a qualifying life event Usually any time of year
If you leave the job May end; some plans are portable Stays with you while you pay
Plan choice The one plan your employer picked Shop several insurers

Features vary by insurer, employer and state.

As one real example, UnitedHealthcare’s Hospital Indemnity Protection is a group product for employers with 100 or more eligible employees. Employers can make it fully employee-paid, it is offered on a guaranteed-issue basis, and coverage is portable at the employer’s group rates if you leave. Read more about group hospital indemnity insurance.

Compare Workplace and Individual Hospital Plans

Taxes: Pre-Tax vs. After-Tax Premiums

How you pay the premium can change how the benefit is taxed. IRS guidance on fixed indemnity plans draws a clear line.

Paid with after-tax dollars. Benefits are generally not taxable income, even if the cash is more than your medical bills.

Paid pre-tax through a cafeteria plan. Benefits from a fixed indemnity plan can be taxable income, because the premium was never taxed.

Ask HR whether your deduction is taken before or after tax, and check with a tax professional about your own situation. Our guide to whether hospital indemnity insurance is pre-tax explains more.

Good to know: Saving a little tax on the premium can mean owing tax on a large payout later. Many people choose after-tax payment so the benefit stays tax-free.

How to Decide Before Open Enrollment Closes

1

Find your deductible and out-of-pocket maximum. They are in your medical plan’s summary of benefits.

2

Total the yearly premium. Multiply the per-paycheck cost by the number of paychecks in a year.

3

Check what one stay pays. Add the admission benefit to the daily benefit for a typical two- to four-day stay.

4

Read the limits. Look for waiting periods, pre-existing condition rules, observation-stay coverage and maternity terms.

5

Compare with an individual quote. If you might change jobs, an individual policy you own could be the better long-term fit.

Broker tip: A licensed agent can quote individual plans next to your workplace option so you can see which pays more per dollar of premium.

For a look at what these plans add beyond the math, see the benefits of voluntary hospital indemnity insurance.

Bottom Line

Voluntary hospital indemnity insurance is worth it for many workers whose deductible or lost pay would strain the budget after a hospital stay. It is a low-cost cash cushion, not health insurance, so weigh the yearly premium against one stay’s payout, check the tax treatment and read the limits before you enroll.

Get Free Hospital Indemnity Insurance Quotes

Is Voluntary Hospital Indemnity Insurance Worth It — Frequently Asked Questions

➤ Is voluntary hospital indemnity insurance worth it?

It often is if a hospital stay would leave you with a deductible or lost income you could not easily cover. If you have strong savings and low out-of-pocket costs, the value is smaller.

➤ What does “voluntary” mean in hospital indemnity?

It means your employer offers the plan but you choose whether to enroll and usually pay the full premium through payroll deduction.

➤ Is voluntary hospital indemnity the same as health insurance?

No. It is a limited-benefit plan that pays fixed cash amounts for covered events. It does not replace your medical plan or meet ACA minimum essential coverage.

➤ Are hospital indemnity payouts taxable?

If you paid the premium with after-tax dollars, benefits are generally not taxable. If you paid pre-tax, benefits can be taxable income. Ask a tax professional about your situation.

➤ Can I keep voluntary hospital indemnity if I leave my job?

Sometimes. Some group plans are portable, such as UnitedHealthcare’s Hospital Indemnity Protection, which can be continued at group rates. Check your certificate.

➤ Does voluntary hospital indemnity cover having a baby?

Many plans pay for a delivery admission, but some apply waiting periods or exclude pregnancies that began before coverage. Read the maternity terms before you enroll.

➤ Do I have to answer health questions?

Workplace plans are often offered with few or no health questions at first eligibility. Enrolling later may require answers or bring limits.

➤ Should I buy hospital indemnity or build savings?

If you can already cover your deductible and a few weeks of lost pay, savings may be enough. If not, the plan can fill the gap while you build savings.

Hospital Indemnity Quotes

Call a Licensed Agent Now

Compare hospital indemnity plans from several insurance companies in one call. Any age.

☎ 1-888-891-0229

No obligation to enroll

Find & Compare Plans Online

Speak with a licensed insurance agent

1-888-891-0229

ZRN Health & Financial Services, LLC, a Texas limited liability company