Speak with a licensed insurance agent

1-888-891-0229

Can You Get Hospital Indemnity Insurance If Already Pregnant? What Pays and What Doesn't

Reviewed by Russell Noga, Licensed Insurance Agent — Last updated October 27, 2026

Yes, you can usually get hospital indemnity insurance if you are already pregnant, but many plans will not pay childbirth benefits for that pregnancy. Policies often exclude a pregnancy that existed before coverage started or require a waiting period of up to about 10 months, so the plan may help with other hospital stays and future births instead.

Hospital indemnity insurance pays you a fixed amount of cash when you are admitted to the hospital. Because a delivery usually means a hospital stay, many expecting parents look at it once they see what their health plan deductible will be. The catch is timing.

This guide explains when an existing pregnancy is covered, the policy terms that decide it, what a new plan may still pay for and what to do instead if you are already expecting. For the bigger picture, see our guide to hospital indemnity insurance for pregnancy.
Compare Hospital Indemnity Plans in Your Area

Enrolling While Pregnant vs. Getting Paid for This Birth

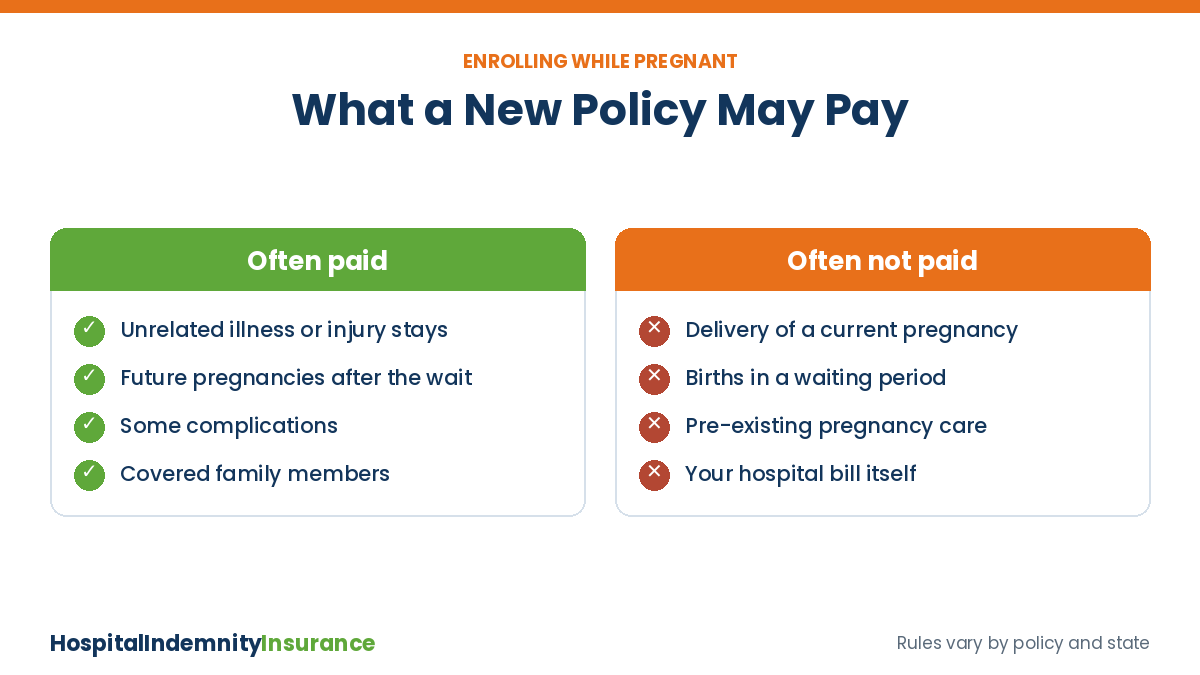
Can you get hospital indemnity insurance if already pregnant: what a new policy may and may not pay

Two different questions get mixed up here. Can you buy a policy while pregnant? Often yes. Many workplace plans are guaranteed issue, and many individual plans do not ask about pregnancy. Will that policy pay when you deliver this baby? Often no.

Getting approved. You can usually enroll during your employer’s open enrollment or buy an individual plan, even while pregnant.

Getting paid for this delivery. Many policies exclude a pregnancy that already existed on the effective date, so the birth may not qualify.

Getting paid for other stays. The same policy can still pay for a covered hospital stay caused by an unrelated illness or accident.

In one case reported in January 2025, a Colorado couple enrolled in a MetLife workplace hospital indemnity plan in November 2023. Their son was born in June 2024, and the claim was denied because the pregnancy began before coverage started and was treated as a pre-existing condition. Reading the pregnancy rules before you enroll avoids that surprise.

Hospital Indemnity Quotes

Call a Licensed Agent Now

Compare hospital indemnity plans from several insurance companies in one call. Any age.

☎ 1-888-891-0229

No obligation to enroll

The Policy Terms That Decide If Your Pregnancy Is Covered

Every policy has its own wording. Look for these terms in the outline of coverage or certificate before you sign up.

Policy term What to look for Why it matters
Effective date The day coverage starts A pregnancy that began before this date is often treated differently
Pre-existing condition rule Whether an existing pregnancy counts as pre-existing If it does, this delivery may not be paid
Pregnancy or childbirth exclusion Language excluding a pregnancy that existed on the effective date Some plans exclude the birth but still cover complications
Childbirth waiting period How long coverage must be in force before a birth is paid Some plans use 10 months, so only future pregnancies qualify
Definition of sickness Whether pregnancy is defined as a sickness This decides which benefits and exclusions apply to it

Terms vary by insurer, plan and state. Get answers in writing from the insurer or your benefits team.

Real policy examples: One Aflac individual hospital policy excludes pregnancy or childbirth if the pregnancy existed on the effective date. Another Aflac outline excludes giving birth in the first 10 months of coverage. One 2026 Chubb employer plan had no pre-existing condition exclusion except for a pregnancy that began before coverage, plus a 10-month wait for childbirth benefits.

What a New Policy May Still Pay While You Are Pregnant

Even if your current delivery is excluded, the policy is not useless. Depending on the wording, it may still pay in these situations.

Unrelated hospital stays. An accident or an illness that has nothing to do with the pregnancy is usually covered once any waiting period for sickness has passed.

Some pregnancy complications. Some policies cover complications of an existing pregnancy the same way as a sickness. One Aflac outline says this, but it also says a C-section is not a complication.

Future pregnancies. Once the waiting period passes, a later pregnancy may qualify for full childbirth benefits.

Other family members. If you add a spouse or children, their covered hospital stays can be paid.

Ask specifically how the plan treats a C-section and a newborn’s own hospital or NICU stay. Newborn coverage often has its own rules, which we explain in our guide to hospital indemnity insurance for newborns.

How Timing and Waiting Periods Work

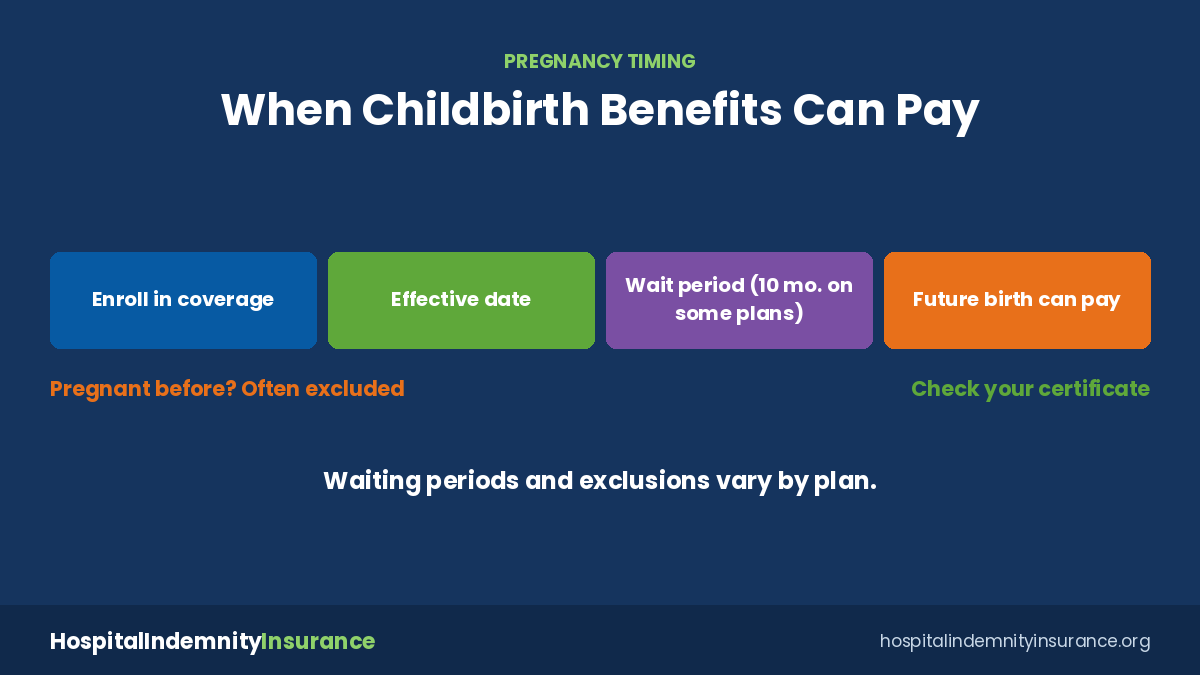
Hospital indemnity pregnancy timing: enroll before pregnancy, wait period, then childbirth benefits

The best time to buy hospital indemnity for a birth is before you are pregnant, ideally a year or more ahead. Many people instead enroll at work during open enrollment while planning a family.

1

Enroll before pregnancy. Coverage starts on the effective date listed in your policy or benefits confirmation.

2

Let the waiting period run. Some plans require coverage to be in force for 10 months before a birth is paid. Others use different waits or none at all.

3

Become pregnant after coverage starts. A pregnancy that begins after the effective date avoids most pre-existing pregnancy exclusions.

4

File the claim after delivery. Send the hospital records showing your admission and discharge dates.

Read more in our guide to the hospital indemnity pregnancy waiting period.

See Hospital Indemnity Options for Your Family

Better Coverage Options If You Are Already Pregnant

Hospital indemnity is a limited-benefit plan that pays fixed cash amounts. It is NOT health insurance, does not pay your hospital bill and does not meet ACA minimum essential coverage. If you are pregnant, real health coverage comes first.

ACA marketplace plans. They cannot turn you down or charge more because you are pregnant. You can enroll during open enrollment, or after a qualifying event. The birth itself is a qualifying event, and a few states also treat pregnancy as one.

Medicaid and CHIP. Many pregnant people qualify, often at higher income levels than other adults, and you can apply any time of year.

Employer health plans. Pregnancy cannot be excluded. If you are not enrolled, the baby’s birth usually opens a special enrollment window.

Broker tip: If you already have good health coverage, compare its hospital deductible and coinsurance with the hospital indemnity benefit. If this birth is excluded, put the premium toward savings for the delivery instead.

Questions to Ask Before You Enroll While Pregnant

1

Is a pregnancy that exists today excluded? Ask for the exact wording on pre-existing conditions and pregnancy.

2

Is there a childbirth waiting period? Get the length in months and the date it ends.

3

Are complications covered? Ask whether complications of an existing pregnancy are treated as a sickness, and whether a C-section counts.

4

How are newborns covered? Ask if the baby is added automatically and whether nursery or NICU stays pay.

5

Can I keep the policy? Ask if the plan is portable if you leave your job, so it is in place for a future pregnancy.

If a policy will pay for your delivery, see what it typically covers in our guide to hospital indemnity insurance for labor and delivery.

Bottom Line

You can usually get hospital indemnity insurance while pregnant, but many plans exclude a pregnancy that existed before coverage started or make you wait about 10 months for childbirth benefits. Make sure your health coverage is solid first, get the pregnancy rules in writing, and treat hospital indemnity as protection for other hospital stays and for future births.

Get Free Hospital Indemnity Insurance Quotes

Hospital Indemnity If Already Pregnant — Frequently Asked Questions

➤ Can you get hospital indemnity insurance if already pregnant?

Usually yes. You can often enroll at work or buy an individual policy while pregnant. Approval does not mean the plan will pay benefits for this pregnancy’s delivery.

➤ Will hospital indemnity pay for my delivery if I enroll while pregnant?

Often not. Many policies exclude a pregnancy that existed on the effective date or have a childbirth waiting period. Some plans do pay, so get the rules in writing before you rely on it.

➤ Is pregnancy a pre-existing condition for hospital indemnity?

It can be. Some policies treat a pregnancy that began before coverage as pre-existing. This is different from ACA health insurance, which cannot exclude pregnancy.

➤ How long is the pregnancy waiting period?

It varies. Some plans pay childbirth benefits only after coverage has been in force for 10 months. Others use a different period or none, so check your certificate.

➤ Are pregnancy complications covered if I was already pregnant?

Sometimes. Some policies cover complications of an existing pregnancy like any sickness, while the normal delivery is excluded. A C-section may not count as a complication.

➤ Will hospital indemnity cover my newborn?

It depends on the plan. Some plans add newborns automatically for a short period after birth, while others limit or exclude nursery stays. Ask about NICU coverage before you enroll.

➤ What should I do for coverage if I am already pregnant?

Make sure you have real health coverage first, such as an ACA marketplace plan, Medicaid or an employer plan. Hospital indemnity can be added later for other stays and future pregnancies.

➤ Is hospital indemnity health insurance?

No. It is a limited-benefit plan that pays fixed cash amounts. It does not replace health insurance and does not meet ACA minimum essential coverage.

Hospital Indemnity Quotes

Call a Licensed Agent Now

Compare hospital indemnity plans from several insurance companies in one call. Any age.

☎ 1-888-891-0229

No obligation to enroll

Find & Compare Plans Online

Speak with a licensed insurance agent

1-888-891-0229

ZRN Health & Financial Services, LLC, a Texas limited liability company