





Speak with a licensed insurance agent

1-888-891-0229

How Does Hospital Indemnity Insurance Work for Pregnancy? A Step-by-Step Guide

Reviewed by Russell Noga, Licensed Insurance Agent — Last updated October 27, 2026

Hospital indemnity insurance works for pregnancy by paying you a fixed cash amount when you are admitted to the hospital to give birth, plus a daily amount for each covered day you stay. You must usually enroll before you become pregnant or pass a waiting period, and the money goes to you, not the hospital.

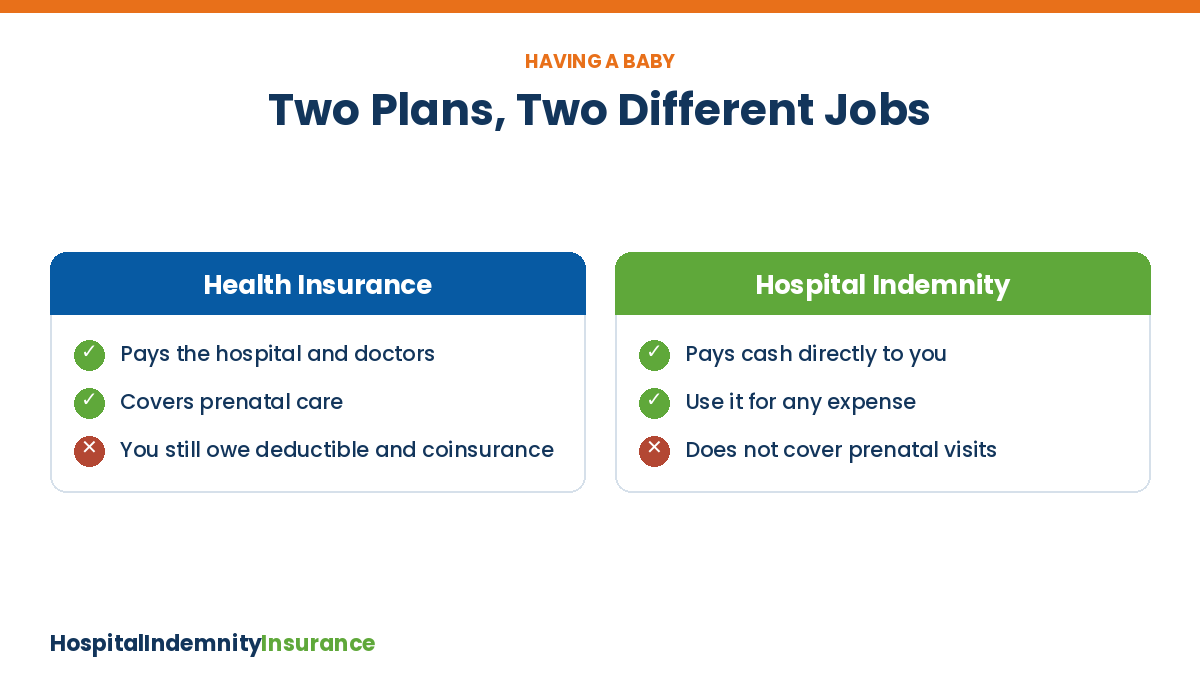
Hospital indemnity does not pay your obstetrician or your hospital bill. It works alongside your health insurance and sends you cash after a covered hospital stay, so you have money for the deductible, coinsurance and life while you recover.

This guide walks through the whole process in order: when to enroll, what triggers a payment, how a sample payout adds up and how to get paid. If you only want the yes-or-no answer on delivery, see does hospital indemnity cover childbirth.
Compare Hospital Indemnity Plans in Your Area

The Basic Idea: Fixed Cash Paid to You

How does hospital indemnity insurance work for pregnancy compared with health insurance during childbirth

Hospital indemnity is a limited-benefit plan. Instead of paying a share of your medical bill, it pays set amounts for set events, such as $1,000 for an admission and $200 for each day in the hospital. The amount is the same whether your bill is $8,000 or $30,000.

Question Your health insurance Hospital indemnity
Who gets paid? The hospital and doctors You
How much? A share of the bill after your deductible A fixed amount per event or per day
Covers prenatal visits? Yes, on ACA-compliant plans Usually no
How can the money be used? Only for covered medical care Anything you choose
Counts as ACA minimum essential coverage? Yes, for ACA-compliant plans No

Hospital indemnity is NOT health insurance and does not replace your maternity coverage.

Hospital indemnity can help anyone expecting a baby: first-time parents on a workplace plan, families buying their own coverage, and self-employed parents who lose income while they recover. Most plans let you cover a spouse and children too, so one policy can protect the whole household.

Hospital Indemnity Quotes

Call a Licensed Agent Now

Compare hospital indemnity plans from several insurance companies in one call. Any age.

☎ 1-888-891-0229

No obligation to enroll

Step 1: Enroll Before You Need It

Timing matters more than anything else for pregnancy. Many plans have a waiting period for childbirth benefits, and some treat a pregnancy that began before your coverage started as pre-existing.

Your situation What usually happens
Enrolled before pregnancy, waiting period over Delivery stay is usually covered
Enrolled before pregnancy, baby arrives during the waiting period Delivery may not be covered; complications may still be
Enrolled while already pregnant Delivery is often not covered for this pregnancy
Hospitalized for a pregnancy complication Many plans pay it like any other sickness

Rules vary by plan and state. Examples we reviewed: Guardian group plans do not pay for a birth in the first 9 months of coverage; one Chubb employer plan had a 10-month wait.

Broker tip: Workplace plans usually let you enroll only at open enrollment or after a qualifying life event. If you hope to grow your family in the next year, sign up at your next open enrollment.

Step 2: What Triggers a Payment During Pregnancy

A plan pays when an event in its benefit schedule happens. During pregnancy, these are the common triggers.

Admission for delivery. Being admitted to the hospital to give birth usually triggers the admission benefit.

Each hospital day. The daily benefit pays for each covered day you stay, often up to a set limit per stay.

Complications. Stays for problems such as preterm labor or preeclampsia are often paid like any other illness.

Your baby’s care. Some plans pay a newborn nursery benefit, and many pay hospital or NICU benefits if your baby is sick and covered.

Routine prenatal visits, ultrasounds and lab work usually do not trigger a payment. Some plans with outpatient riders pay small amounts for doctor visits or tests. Read more in hospital indemnity insurance for labor and delivery.

Step 3: How a Pregnancy Payout Adds Up

How does hospital indemnity insurance work for pregnancy sample payouts compared with average out-of-pocket costs

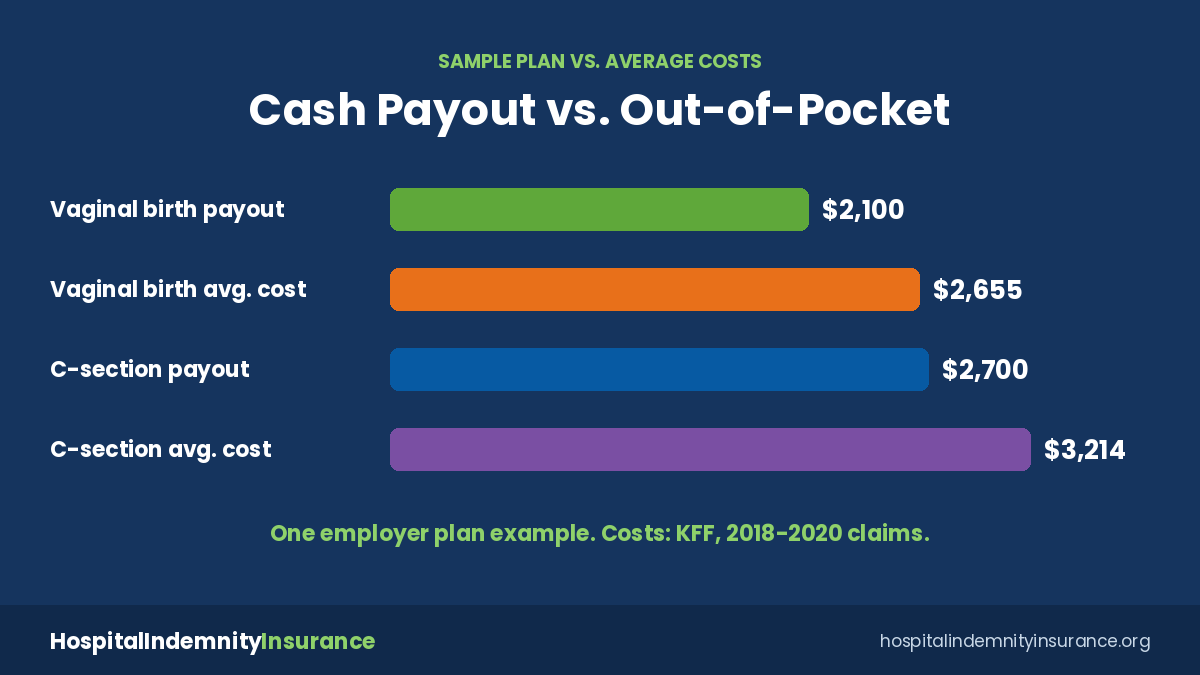
Here is how one 2026 Chubb employer plan (Plan 1) would pay for a delivery, assuming the waiting period has passed and the daily benefit pays for each day in the hospital. The plan pays a $1,500 admission benefit, $200 per day and a newborn nursery benefit of $100 per day for up to 2 days, or 4 after a C-section.

Benefit Vaginal birth, 2 days C-section, 4 days
Admission $1,500 $1,500
Daily hospital benefit $400 $800
Newborn nursery $200 $400
Estimated cash to you $2,100 $2,700
Average added out-of-pocket cost (KFF) $2,655 $3,214

Hypothetical example using one employer plan’s listed amounts. Out-of-pocket averages are from KFF’s analysis of large employer plans, 2018-2020. Your plan and costs will differ.

In this example, the cash would cover most of the average out-of-pocket cost of having a baby. For more payout examples, see how much hospital indemnity insurance pays for pregnancy.

See Pregnancy-Friendly Hospital Plans

How It Works Alongside Your Health Plan

Hospital indemnity pays no matter what your other coverage pays. That makes it most useful when your health plan leaves you with a large share of the bill.

High-deductible plans. A delivery can use up most or all of your deductible. Cash from hospital indemnity can fill that gap. See hospital indemnity for high-deductible plans.

ACA Marketplace plans. Maternity and newborn care are essential health benefits. Hospital indemnity adds cash for your deductible, coinsurance and bills at home.

Employer plans. Your share may be lower, but unpaid leave can still strain your budget. A cash payout can help replace lost income.

Self-employed parents. If you do not get paid leave, a payout can help cover rent and groceries while you recover.

Step 4: Filing a Claim and Getting Paid

1

Confirm your benefits before your due date. Check your coverage start date, any waiting period and whether your baby needs to be added to the plan.

2

Save your hospital records. Keep your admission and discharge dates, the hospital name, discharge papers and any itemized bill.

3

Submit the claim form. File online, by mail or through your employer’s benefits portal, using the insurer’s claim form.

4

Add your newborn. If your plan includes child coverage, add your baby within the plan’s deadline so newborn benefits apply.

5

Watch for payment. Benefits are usually paid by direct deposit or check. Keep copies of everything and your claim number.

Wondering if the premium is worth it for your family? Read is hospital indemnity insurance worth it for pregnancy.

Bottom Line

Hospital indemnity insurance works for pregnancy by paying you fixed cash when you are admitted to give birth and for each covered day you stay. It works best when you enroll before you are pregnant, so waiting periods are behind you by your due date. It adds to your health insurance but never replaces it.

Get Free Hospital Indemnity Insurance Quotes

Hospital Indemnity Insurance for Pregnancy — Frequently Asked Questions

➤ How does hospital indemnity insurance work for pregnancy?

It pays you a fixed cash amount when you are admitted to the hospital to deliver, and usually a daily amount for each covered day. You can use the money however you want.

➤ When should I buy hospital indemnity for pregnancy?

Before you become pregnant, ideally at your employer’s open enrollment. Many plans have a 9- or 10-month waiting period or exclude a pregnancy that began before coverage started.

➤ Does hospital indemnity pay for prenatal visits?

Usually not. Most plans pay only for hospital stays. A few plans with outpatient riders pay small amounts for doctor visits or tests.

➤ Does hospital indemnity pay for pregnancy complications?

Many plans pay hospital stays for complications the same way they pay any other sickness. Rules on waiting periods still apply on some plans.

➤ How much does hospital indemnity pay for a delivery?

It depends on your plan. In one employer plan we reviewed, a two-day vaginal birth would pay about $2,100 and a four-day C-section about $2,700, including newborn nursery benefits.

➤ Is my baby covered by my hospital indemnity plan?

If your plan includes child coverage, your baby may be covered, but you may need to add them by a deadline. Some plans pay a newborn nursery benefit for a healthy baby.

➤ Can I have hospital indemnity and health insurance at the same time?

Yes. Hospital indemnity is designed to work alongside health insurance and pays you no matter what your health plan pays.

➤ Is hospital indemnity the same as maternity insurance?

No. It is a limited-benefit plan that pays fixed cash amounts. It does not cover prenatal care or pay your medical bills, and it does not meet ACA minimum essential coverage.

Hospital Indemnity Quotes

Call a Licensed Agent Now

Compare hospital indemnity plans from several insurance companies in one call. Any age.

☎ 1-888-891-0229

No obligation to enroll

Find & Compare Plans Online

Speak with a licensed insurance agent

1-888-891-0229

ZRN Health & Financial Services, LLC, a Texas limited liability company