
Reviewed by Russell Noga, Licensed Insurance Agent — Last updated October 28, 2026
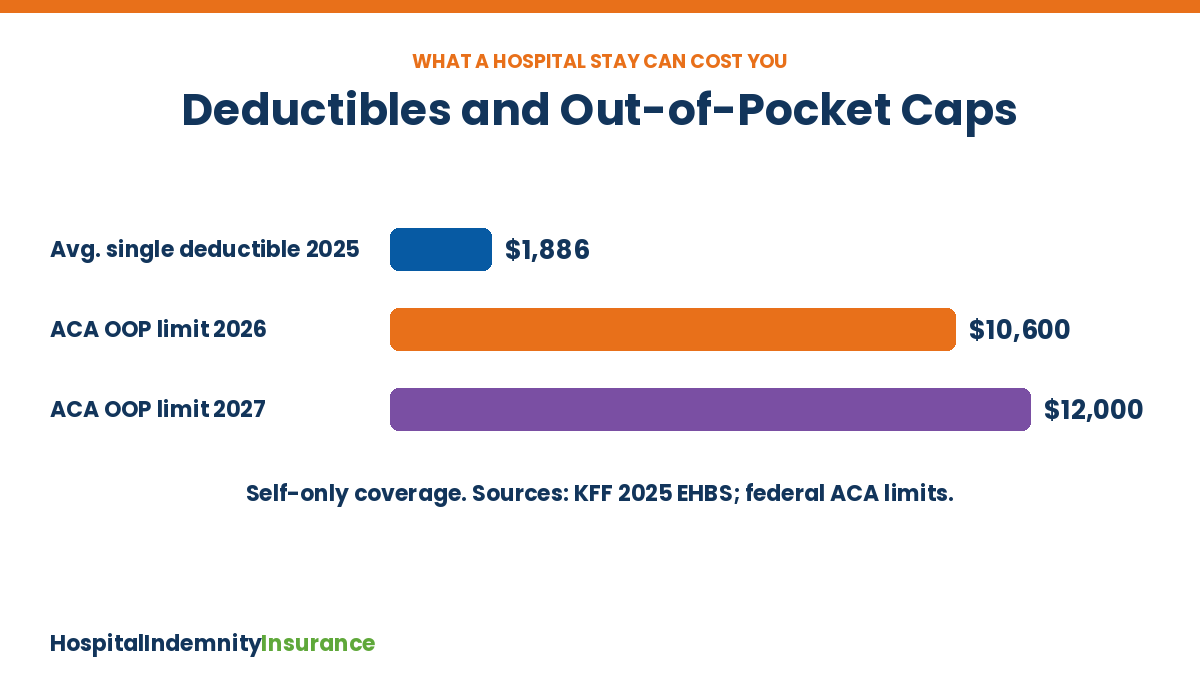
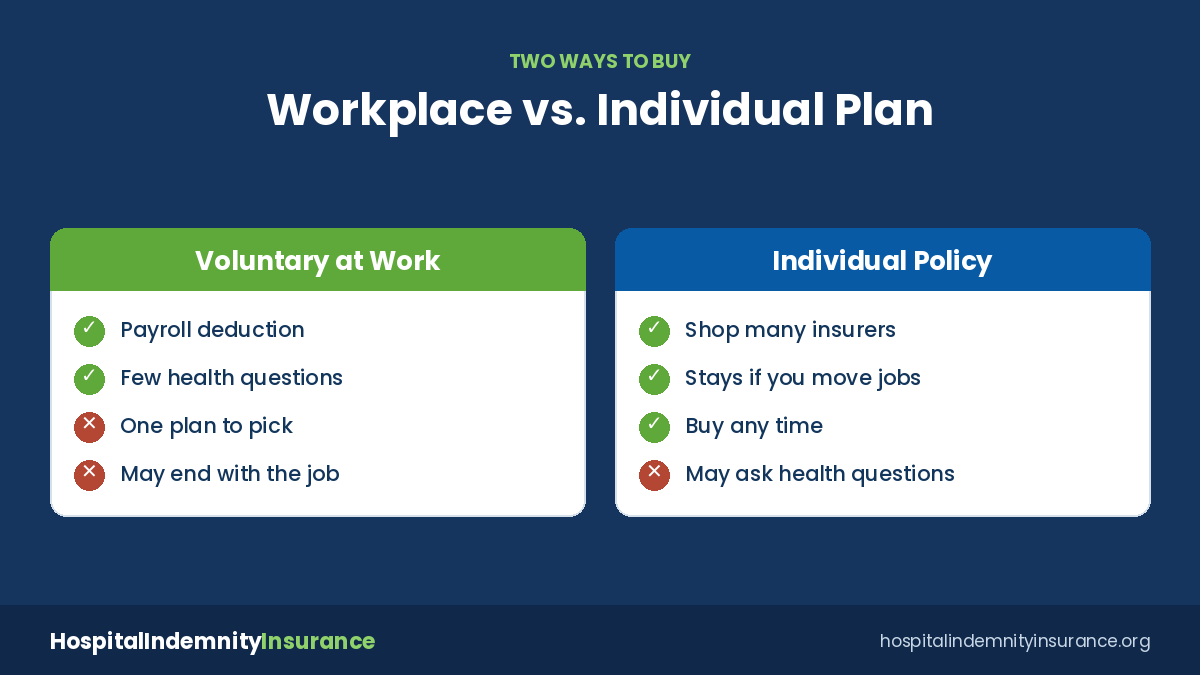
Voluntary hospital indemnity insurance is often worth it if a hospital stay would leave you with a deductible or lost pay you could not easily cover. It is a workplace plan you pay for through payroll, and it sends you fixed cash after a covered stay. If you have strong savings and low out-of-pocket costs, the premium may do more good in your emergency fund.
Every open enrollment, many employers add a line for “hospital indemnity” next to accident and critical illness coverage. The word “voluntary” means you choose it and you usually pay the full premium through payroll deduction. The question is whether that small deduction buys real protection for your family.
This guide walks through the math, the tax rules and the fine print so you can decide in a few minutes. If you are new to these plans, start with our overview of voluntary hospital indemnity.