





Speak with a licensed insurance agent

1-888-891-0229

UnitedHealthcare Critical Illness Insurance: Every Product, Who Issues It and What It Pays

Reviewed by Russell Noga, Licensed Insurance Agent — Last updated November 21, 2026

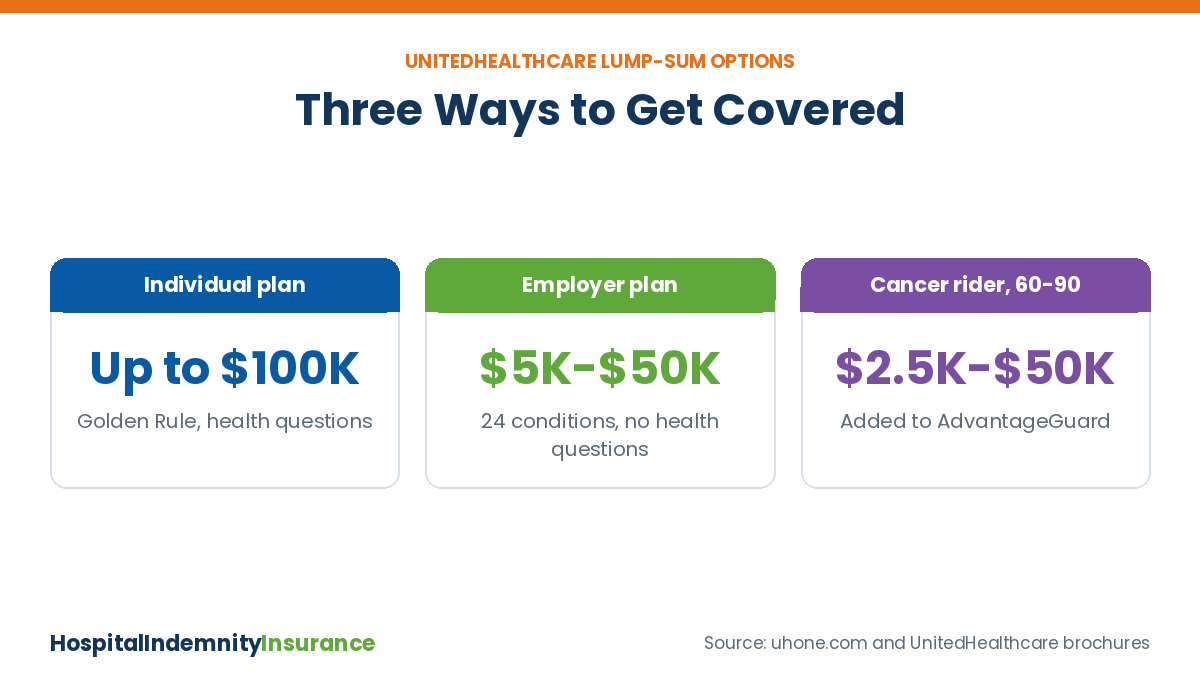
Yes, UnitedHealthcare offers critical illness insurance: an individual plan underwritten by Golden Rule Insurance Company with lump sums up to $100,000, and an employer plan called Critical Illness Protection, issued by UnitedHealthcare Insurance Company, that pays $5,000 to $50,000. Both pay cash to you when a covered condition is diagnosed, and people 60 to 90 can add a cancer-only lump sum to Golden Rule’s AdvantageGuard hospital plan.

2027 by the Numbers

$100,000

highest individual lump sum Golden Rule lists for UnitedHealthcare critical illness (uhone.com)

24

conditions in the employer Critical Illness Protection plan, 6 of them child-only (UnitedHealthcare brochure)

A (Excellent)

AM Best rating for UnitedHealthcare’s insurance companies since the August 2025 downgrade

People reach this topic from very different places: a 28-year-old at open enrollment, a self-employed parent who wants cash if cancer stops the paychecks, or a 66-year-old on Medicare. Each ends up with a different UnitedHealthcare product, issued by a different company, with different rules.

This hub sorts that out using UnitedHealthcare’s and Golden Rule’s own brochures, certificates and product pages. It covers which products exist, how much they pay, the waiting and repeat-diagnosis rules, and how a lump sum works next to UnitedHealthcare hospital indemnity. Critical illness coverage is a limited-benefit policy. It is not health insurance, it does not replace a medical plan and it does not count as ACA minimum essential coverage.
Compare Critical Illness and Hospital Cash Plans in Your State

Does UnitedHealthcare Offer Critical Illness Insurance? Three Doors In

UnitedHealthcare critical illness insurance products: individual Golden Rule plan, employer Critical Illness Protection and AdvantageGuard Cancer rider

UnitedHealthcare is a brand, not a single insurer. Its supplemental products are written by several companies in the UnitedHealth Group family, and which one stands behind your policy depends on how you buy it. For critical illness, there are three doors.

Buying on your own. The individual critical illness plan is underwritten by Golden Rule Insurance Company and sold on uhone.com and through licensed agents. You answer yes-or-no health questions, and approval depends on the answers.

Getting it through work. Critical Illness Protection is a group plan issued by UnitedHealthcare Insurance Company of Hartford, Connecticut. Employers need at least 100 eligible employees, and enrolled workers, spouses and children get it without health questions.

Age 60 and older. Golden Rule’s AdvantageGuard is a hospital indemnity plan for issue ages 60 to 90. It has an optional Cancer rider that pays a lump sum, but there is no heart attack or stroke rider.

Hospital Indemnity Quotes

Call a Licensed Agent Now

Compare hospital indemnity plans from several insurance companies in one call. Any age.

☎ 1-888-891-0229

No obligation to enroll

UHC Critical Illness Insurance Products Compared Side by Side

No single UnitedHealthcare page lines these options up together, so we built this table from four carrier documents. The 2016 Golden Rule brochure is included because it is the latest individual document we found that prints issue ages, and it shows how the design has changed.

Detail Individual plan (Golden Rule, current) Earlier individual brochure (Golden Rule, 2016) Employer Critical Illness Protection AdvantageGuard Cancer rider (ages 60-90)
Issuer Golden Rule Insurance Company Golden Rule Insurance Company UnitedHealthcare Insurance Company Golden Rule Insurance Company
Lump-sum range Up to $100,000 $10,000 to $50,000 in $10,000 steps $5,000 to $50,000 $2,500 to $50,000 in $2,500 steps
Covered conditions 12 listed on the product page, from life-threatening cancer to loss of independent living Heart attack, stroke, cancer, transplant, paralysis, coma, kidney failure and more 24: 12 base, 6 additional, 6 child-only 4 cancer events only
Waiting period 30 days in most states 30 days Set by the group certificate 30 days in most states
Issue ages Not published; subject to issue-age limits 18 to 59 Eligible employees and families 60 to 90
Health questions Yes, medically underwritten Yes None (guaranteed issue) Depends on benefits chosen
Repeat payouts First diagnosis in your lifetime, in most states Cancer and bypass once per person Different conditions pay; same condition can pay again after 12 months One payment per event per lifetime

Compiled by HospitalIndemnityInsurance.org from uhone.com, Golden Rule brochures 40198-G-0816 and 49835-G202309 and UnitedHealthcare’s Critical Illness Protection employer brochures, checked November 2026. Varies by state.

Two changes stand out. The individual maximum has doubled from $50,000 to $100,000, and the current page calls the plan guaranteed renewable for life in most states, where the older form stopped renewing at the insured’s 70th birthday. For what these plans tend to cost, see our UnitedHealthcare critical illness insurance cost page.

Which Diagnoses Pay, and How Much of the Lump Sum

Every UnitedHealthcare plan pays a percentage of the amount you pick. Invasive cancer, heart attack and stroke pay in full, while early or less severe diagnoses pay a slice.

Paid in full. Life-threatening cancer, heart attack, stroke, major organ transplant, kidney failure, paralysis and coma pay 100% in the plans we reviewed.

Partial payments. Non-invasive cancer and carcinoma in situ pay 25%, and coronary artery disease or bypass surgery pays 25% in the group certificate and the older individual form.

Small flat amounts. The AdvantageGuard Cancer rider pays $500 for skin cancer and 25% for a benign brain tumor.

Children and the brain. The employer plan adds child conditions such as cystic fibrosis, Down syndrome and spina bifida, and pays for Alzheimer’s, ALS, Parkinson’s and multiple sclerosis.

Fine print to check: Basal cell and squamous cell skin cancers and melanoma in situ are excluded from the cancer levels in the group certificate we read. A partial payment also counts against the total, so later claims pay what is left of the maximum.

Our page on UnitedHealthcare critical illness insurance coverage goes deeper on the condition definitions.

Waiting Periods, Second Diagnoses and Age Rules

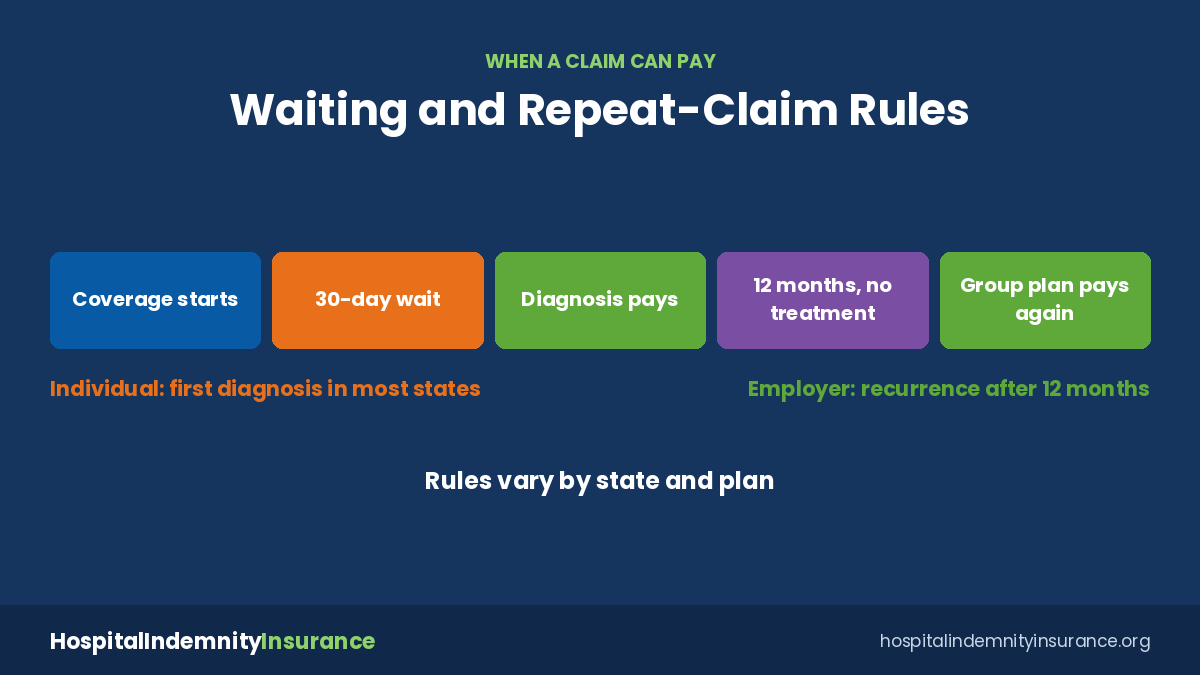
UnitedHealthcare critical illness insurance timing: 30-day wait, first diagnosis lump sum and 12-month gap before a group plan pays again

Timing decides whether a claim pays. A diagnosis made before your effective date never qualifies, and a diagnosis inside the waiting period usually does not either.

1

Day one to day 30. Golden Rule’s individual plan and the AdvantageGuard Cancer rider require the first diagnosis at least 30 days after coverage starts, in most states. The 2016 form paid only 10% for cancer found between days 30 and 90.

2

After the first claim. Under the employer plan, a different covered condition can pay with no gap. The same condition can pay again if it is diagnosed 12 or more months later with no treatment in between; maintenance drugs do not reset that clock.

3

Individual plans are stricter. UnitedHealthcare’s page says individual benefits pay on the first diagnosis in a covered person’s lifetime in most states, so a recurrence generally does not pay twice.

4

Birthdays. The 2016 individual form cut the maximum by 50% at 65. The 2023 employer brochure says group benefits do not drop at a set age, though premiums rise as you move into new age bands under attained-age pricing.

Pre-existing rules differ too: the individual plan applies pre-existing condition terms, AdvantageGuard limits them for the first 6 months, and the 2023 employer brochure lists no such limitation.

See Which UnitedHealthcare-Family Plans Are Sold in Your ZIP Code

Pairing a UnitedHealthcare Critical Illness Plan With Hospital Indemnity

A critical illness plan and a hospital indemnity plan answer different questions. Critical illness pays once when a named diagnosis is made, even with no hospital night. Hospital indemnity pays set amounts for admissions and inpatient days, whatever the cause. One serious illness often triggers both.

Cancer treated as an outpatient. Chemotherapy and radiation are often done without an admission, so a critical illness lump sum may pay where a hospital plan pays little.

Heart attack with a hospital stay. The diagnosis triggers the critical illness benefit, and the inpatient days trigger hospital indemnity, so the two can pay on the same event.

For 60-plus buyers: AdvantageGuard puts hospital cash and a cancer lump sum in one Golden Rule policy, which suits people on Medicare Advantage who face inpatient copays. It does not cover heart attack or stroke as a lump sum. See hospital indemnity insurance with Medicare Advantage for the copay side, and critical illness insurance vs hospital indemnity for a general comparison.

Which UnitedHealthcare Critical Illness Plan Fits You

Your situation Where to look first What to watch
Employer offers Critical Illness Protection Group plan at open enrollment Benefit amount, whether child coverage is included, portability if you leave
Self-employed, early retiree or between jobs Golden Rule individual plan Health questions, 30-day wait, lifetime first-diagnosis rule
Age 60 to 90, worried most about cancer AdvantageGuard with the Cancer rider Sold in 19 states; Cancer rider not offered in Connecticut or Illinois
Worried about heart attack or stroke at 60-plus A stand-alone critical illness policy that accepts your age Issue-age limits; compare carriers

Product details from UnitedHealthcare and Golden Rule documents; state availability varies.

A claim may come years after you buy, so company strength matters. In August 2025 AM Best lowered UnitedHealth Group’s health insurers from A+ (Superior) to A (Excellent), outlook stable.

Bottom Line

UnitedHealthcare critical illness insurance is three different products wearing one name: a Golden Rule individual plan up to $100,000, an employer group plan with 24 conditions and recurrence pay, and a cancer-only rider for people 60 to 90. Pick by how you can buy it, then compare the condition list, percentages and waiting rules. Pair it with hospital indemnity if hospital stays worry you as much as a diagnosis.

Get Free Quotes on Lump-Sum and Hospital Cash Coverage

UnitedHealthcare Critical Illness Insurance — Frequently Asked Questions

➤ Does UnitedHealthcare offer critical illness insurance to individuals?

Yes. Golden Rule Insurance Company, a UnitedHealthcare company, underwrites an individual critical illness plan with lump sums up to $100,000. It uses health questions, and the amounts and availability vary by state and by your age when the policy is issued.

➤ Is united healthcare critical illness insurance the same as UHC critical illness insurance?

Yes. United Healthcare, UnitedHealthcare and UHC all refer to the same brand. What changes is the issuing company: Golden Rule for individual plans and UnitedHealthcare Insurance Company for employer plans.

➤ How many conditions does the UnitedHealthcare employer plan cover?

UnitedHealthcare’s Critical Illness Protection brochure lists 24 conditions: 12 base conditions, 6 additional conditions and 6 conditions for children. Your employer’s certificate shows which ones your group chose.

➤ Can a UnitedHealthcare critical illness plan pay more than once?

On the employer plan, yes. A different covered condition can pay without a gap, and the same condition can pay again after 12 months without treatment. Individual plans generally pay on the first diagnosis in your lifetime in most states.

➤ Can I keep my UnitedHealthcare critical illness plan if I leave my job?

The employer brochure says coverage is portable at group rates. In the certificate we reviewed, you had to be under 70 and apply within 31 days after coverage ended.

➤ Is there a UnitedHealthcare critical illness plan for people on Medicare?

There is no stand-alone Medicare-age critical illness plan on UnitedHealthcare’s sites. Golden Rule’s AdvantageGuard, for issue ages 60 to 90, offers a Cancer rider with a $2,500 to $50,000 lump sum alongside hospital cash benefits.

➤ Does a unitedhealthcare critical illness plan replace health insurance?

No. It is a limited-benefit policy that pays cash to you and does not pay doctors or hospitals. It does not count as ACA minimum essential coverage and works on top of your medical plan.

➤ Is UnitedHealthcare still a strong company to buy from?

AM Best rates UnitedHealth Group’s health insurers A (Excellent), with a stable outlook, after an August 2025 downgrade from A+. It is still a strong rating, but weigh it beside price, conditions and renewal terms.

Hospital Indemnity Quotes

Call a Licensed Agent Now

Compare hospital indemnity plans from several insurance companies in one call. Any age.

☎ 1-888-891-0229

No obligation to enroll

Find & Compare Plans Online

Speak with a licensed insurance agent

1-888-891-0229

ZRN Health & Financial Services, LLC, a Texas limited liability company