





Speak with a licensed insurance agent

1-888-891-0229

Is Hospital Indemnity HSA Eligible? The IRS Permitted-Insurance Rule, Benefits to Watch and 2027 HSA Limits

Reviewed by Russell Noga, Licensed Insurance Agent — Last updated November 7, 2026

Yes, a hospital indemnity plan that pays a fixed cash amount per day of hospitalization is HSA eligible, because federal tax law lists it as permitted insurance that does not stop you from contributing to a Health Savings Account. The risk comes from extras that pay per service before your deductible, such as emergency room, urgent care or X-ray benefits, so look for a design the insurer labels HSA compatible; you also generally cannot pay the premium with HSA money.

2027 by the Numbers

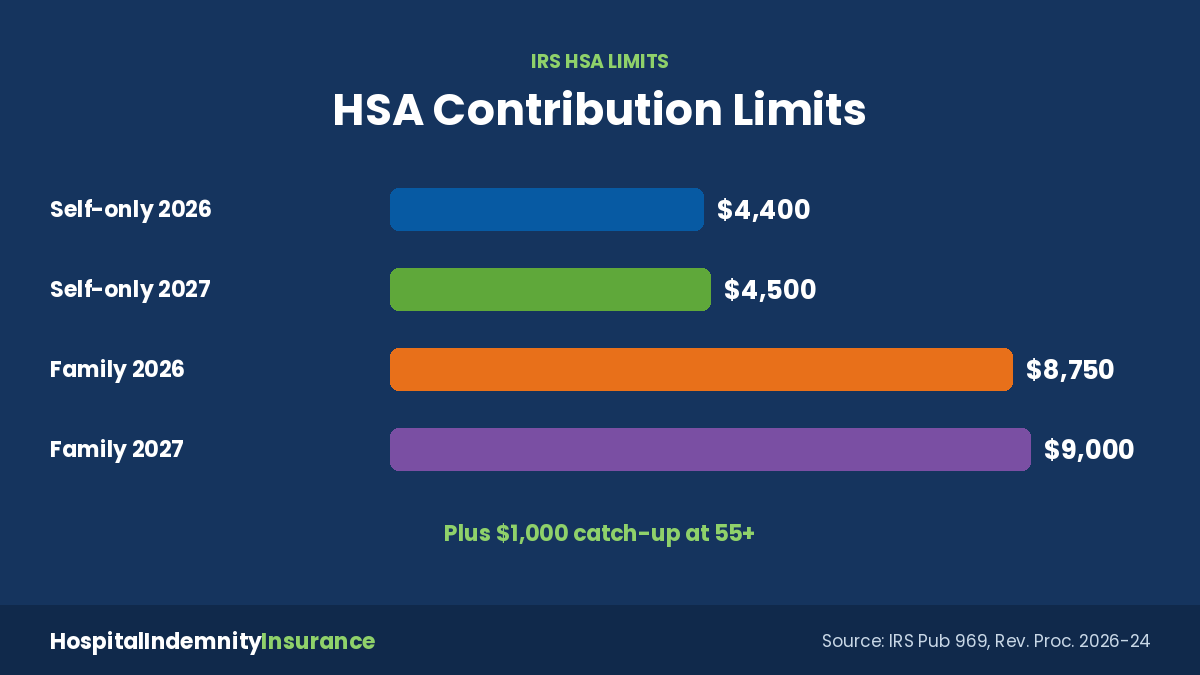
$4,500 / $9,000

2027 HSA contribution limit, self-only / family (IRS Rev. Proc. 2026-24)

$1,750

2027 minimum deductible for an HSA-qualified plan, self-only (IRS)

$1,000

added catch-up contribution allowed at age 55 or older (IRS)

6 months

how far back Part A can start if you apply after 65 (SSA)

An HSA has a strict entry rule: while you contribute, the only health coverage you may hold is a qualifying high-deductible plan plus a short list of exceptions. Hospital indemnity sits on that list, but only when it is built the way the tax code describes.

Below: the exact rule, the benefits that cross the line, four insurers’ HSA-ready designs, and how it fits workers, families, the self-employed and people nearing Medicare. For how the deductible gap works day to day, see hospital indemnity for high-deductible plans.
Compare HSA-Compatible Hospital Indemnity Plans

What Federal Tax Law Says About Hospital Plans and HSAs

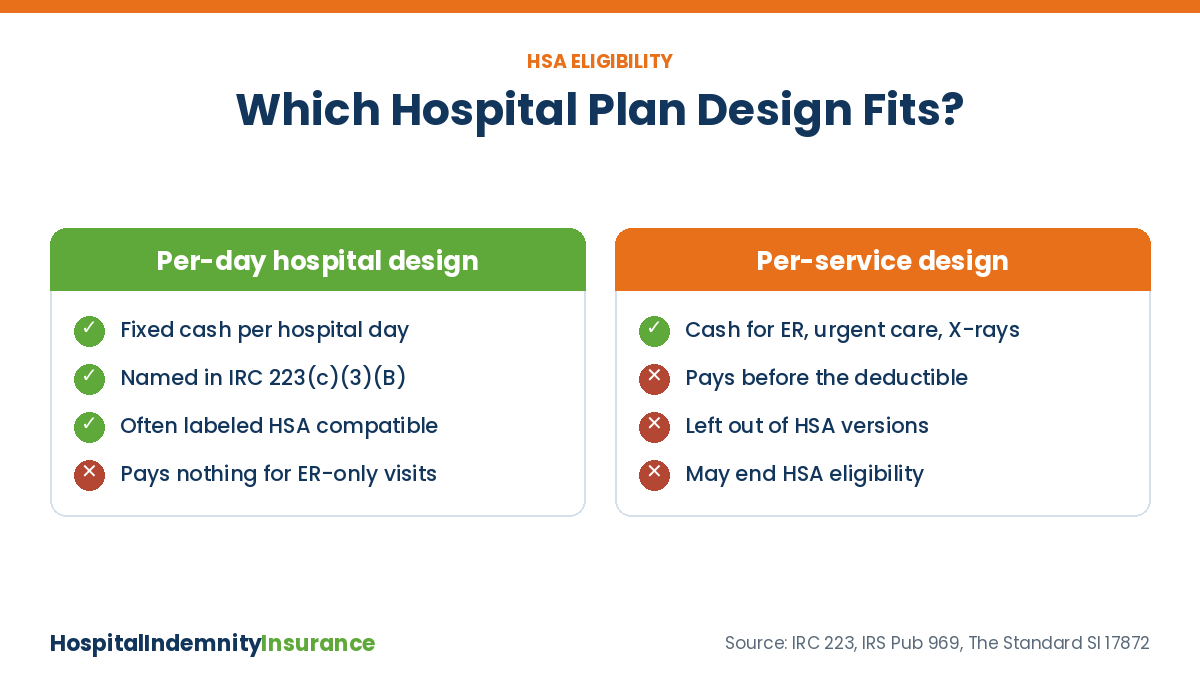
Is hospital indemnity HSA eligible: per-day hospital benefits vs per-service outpatient benefits

Internal Revenue Code Section 223 lets you contribute only if you are covered by a high-deductible health plan (HDHP) and no other health plan, with named exceptions. Section 223(c)(3)(B) carves out insurance paying a fixed amount per day, or other period, of hospitalization. IRS Publication 969 repeats that wording in its list of other health coverage you may keep.

Permitted insurance. Fixed per-day hospital indemnity, specified-disease policies such as cancer insurance, and liability-type coverage like workers’ compensation.

Permitted coverage. Accident, disability, dental, vision, long-term care and, under current law, telehealth received before the deductible.

Disqualifying coverage. A second medical plan, a spouse’s general-purpose health FSA, or any part of Medicare.

Not an HDHP by itself. Pub 969 says a plan that covers mostly these exception items is not an HDHP, so hospital indemnity alone never qualifies you.

Status of the product: Hospital indemnity is a limited-benefit plan that pays fixed cash amounts. It is not health insurance, does not replace your HDHP and does not count as ACA minimum essential coverage. The difference is laid out in hospital indemnity vs health insurance.

Hospital Indemnity Quotes

Call a Licensed Agent Now

Compare hospital indemnity plans from several insurance companies in one call. Any age.

☎ 1-888-891-0229

No obligation to enroll

Per-Day Payouts vs. Per-Service Payouts: Where the Line Falls

The exception is tied to days or periods in the hospital. Many products also pay flat amounts for outpatient events, like an ER trip or a lab test. Those riders act more like pre-deductible coverage than a hospitalization benefit, so insurers usually strip them from HSA versions.

Benefit In The Standard’s HSA-compatible designs In its Select, Enhanced and Premier designs
Daily hospital confinement Included in every design Offered
Hospital admission lump sum Optional, with a caution footnote Offered
Critical care unit admission and daily stay Optional; admission carries the same footnote Offered
Health maintenance screening Optional Optional
Emergency room and urgent care Not offered Offered
Follow-up care, major diagnostic exam, outpatient X-ray and lab Not offered Offered
Ground and air ambulance Not offered Offered
Inpatient surgery and anesthesia Not offered Offered

Source: The Standard, Group Hospital Indemnity Insurance Reference Guide SI 17872 (11/24), policy form GP0614-HI. Employer group product; individual plans vary.

Note the footnote: The Standard warns that even an admission benefit may not be compatible with an HSA. The IRS has not published a rider-by-rider list, so the insurer’s HSA label is the best evidence most buyers will see.

Four Insurers' HSA-Ready Designs, Side by Side

Employer benefit summaries show one pattern: per-day hospital pay stays, outpatient cash goes.

Insurer and document HSA wording Hospital benefits shown Non-inpatient extras
Hartford (Jefferson County, Texas summary) HSA compatible: yes $1,000 first day; $200 a day from day 2, up to 30 days $100 a day observation stay, up to 5 days; $50 screening
Symetra, form SBC-00500 (Nebraska Methodist Health System) HSA compatible: yes Fixed amounts per day or per incident Excludes ER, outpatient clinic and urgent care
United of Omaha, form G2018MP Says IRS limits supplemental coverage; consult advisors $2,000 admission; $200 a day, up to 30 days $50 health screening once a year
The Standard, form GP0614-HI Separate HSA-compatible designs Daily confinement plus optional admission Screening only

Compiled by HospitalIndemnityInsurance.org from each employer’s published benefit summary. Amounts are those groups’ chosen levels, not standard prices.

1

Find the label. Look for the words HSA compatible on the summary or enrollment screen.

2

Scan the benefit list. ER, urgent care, doctor visit, imaging or ambulance cash are signs of a non-HSA design.

3

Read the fine-print footnote. Many carriers add a sentence on IRS limits; it tells you what they did and did not review.

4

Confirm with the plan sponsor. Ask HR or the HSA administrator before the coverage start date, not after a claim.

2026 and 2027 HSA Limits That Shape the Pairing

2026 and 2027 HSA contribution limits for people asking is hospital indemnity HSA eligible

The limits explain why the two are bought together: a new HDHP owner may face a deductible larger than the account balance for a year or two.

IRS figure 2026 2027
HSA contribution, self-only $4,400 $4,500
HSA contribution, family $8,750 $9,000
Minimum HDHP deductible, self-only / family $1,700 / $3,400 $1,750 / $3,500
HDHP out-of-pocket maximum, self-only / family $8,500 / $17,000 $8,700 / $17,400
Catch-up at 55 or older $1,000 $1,000

Sources: IRS Publication 969 (2026 figures) and Rev. Proc. 2026-24 (2027 figures).

Order of operations: Hospital indemnity cash goes to you to spend on anything. Using it for a hospital bill can leave your HSA invested for later years, and the HSA keeps rolling over whether or not you are ever admitted.

Check Hospital Indemnity Options in Your ZIP Code

Paying the Premium: HSA Dollars, Payroll and Taxes

Pub 969 says HSA money generally cannot pay insurance premiums. The exceptions are narrow, and hospital indemnity is not among them, so a withdrawal for that premium would be taxable and, before 65, face a 20% additional tax.

Premium type Payable tax-free from an HSA?
Hospital indemnity, cancer or accident policy No
Qualified long-term care insurance Yes, up to IRS age-based limits
COBRA continuation coverage Yes
Health coverage while getting unemployment benefits Yes
Medicare Parts A, B, D or Medicare Advantage, age 65 or older Yes; Medigap premiums are excluded

Source: IRS Publication 969, qualified medical expenses section.

At work, the premium may come out of pay before tax through a cafeteria plan instead; see is hospital indemnity insurance pre-tax. That choice can affect whether the cash benefit is taxed, covered in is hospital indemnity insurance taxable. This page is general information, not tax advice; check your situation with a tax professional.

Building HDHP + HSA + Hospital Indemnity for Your Household

Working adults with an employer HDHP. Choose the HSA version of the voluntary hospital plan at open enrollment, and skip a spouse’s general-purpose health FSA, which disqualifies you both.

Families. The family HSA limit applies once anyone else is on the HDHP; a family hospital rider that pays per day keeps everyone eligible.

Self-employed and Marketplace buyers. Since January 1, 2026, IRS Notice 2026-05 treats bronze and catastrophic plans as HSA compatible, even when bought off the Exchange. See hospital indemnity for self-employed individuals.

People turning 65. Enrolling in any part of Medicare drops your HSA limit to zero. Part A can start up to 6 months before you apply, so contributions in those months count as excess.

Once on Medicare, the HSA balance can still pay qualified costs, and a hospital plan can still help with inpatient copays; see hospital indemnity with Medicare Advantage.

Bottom Line

A per-day hospital indemnity plan is HSA eligible under the tax code’s permitted-insurance exception, while outpatient and per-service riders are the usual reason a design is not. Pick a version the insurer labels HSA compatible, pay its premium from regular income or payroll, and stop HSA contributions before Medicare begins.

Get Free Hospital Indemnity Quotes That Fit an HSA

Hospital Indemnity and HSA Eligibility — Frequently Asked Questions

➤ Does a hospital indemnity policy count as my high-deductible health plan?

No. You still need a qualifying HDHP, or since 2026 a bronze or catastrophic plan, to contribute. Pub 969 says coverage made up mostly of exception items like fixed indemnity is not an HDHP.

➤ Does it matter that the plan pays me instead of the hospital?

Not for eligibility. What counts is what triggers the payment: a fixed amount per day in the hospital fits the exception, while flat amounts for outpatient services may not.

➤ Are wellness or health screening benefits a problem?

The Standard, Hartford and United of Omaha all include a small screening benefit in designs presented for HSA buyers. Preventive care is generally allowed before the deductible, but check your plan’s terms.

➤ What if I learn my plan is not HSA compatible?

Contributions for ineligible months are excess contributions. Pub 969 applies a 6% excise tax each year they stay in the account, which you can generally avoid by withdrawing them, plus earnings, by your tax-filing deadline. Ask a tax professional how to fix it.

➤ Can my spouse’s hospital indemnity plan hurt my HSA?

A per-day plan covering you through a spouse is still permitted insurance. A spouse’s general-purpose health FSA is different; it disqualifies both of you.

➤ I am 65 and still working. Can I keep contributing?

Yes, if you are not enrolled in any part of Medicare. If you already get Social Security benefits, Part A usually starts automatically, which ends HSA contributions.

➤ Can I buy hospital indemnity outside of open enrollment and keep my HSA?

Many individual plans sell year-round. Choose a per-day design and read its HSA note first.

➤ Is telehealth or direct primary care allowed too?

Yes. Recent law permanently allows pre-deductible telehealth for plan years starting in 2025, and from 2026 certain direct primary care arrangements no longer block contributions.

Hospital Indemnity Quotes

Call a Licensed Agent Now

Compare hospital indemnity plans from several insurance companies in one call. Any age.

☎ 1-888-891-0229

No obligation to enroll

Find & Compare Plans Online

Speak with a licensed insurance agent

1-888-891-0229

ZRN Health & Financial Services, LLC, a Texas limited liability company