Reviewed by Russell Noga, Licensed Insurance Agent — Last updated November 7, 2026
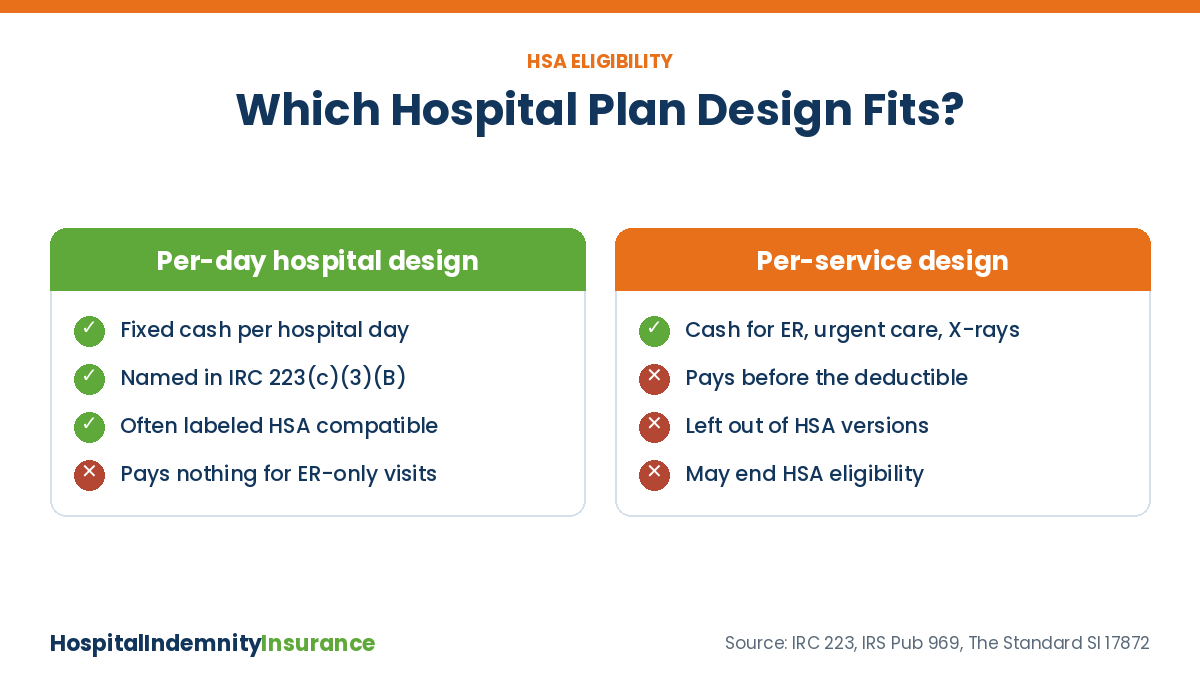
Yes, a hospital indemnity plan that pays a fixed cash amount per day of hospitalization is HSA eligible, because federal tax law lists it as permitted insurance that does not stop you from contributing to a Health Savings Account. The risk comes from extras that pay per service before your deductible, such as emergency room, urgent care or X-ray benefits, so look for a design the insurer labels HSA compatible; you also generally cannot pay the premium with HSA money.
2027 by the Numbers
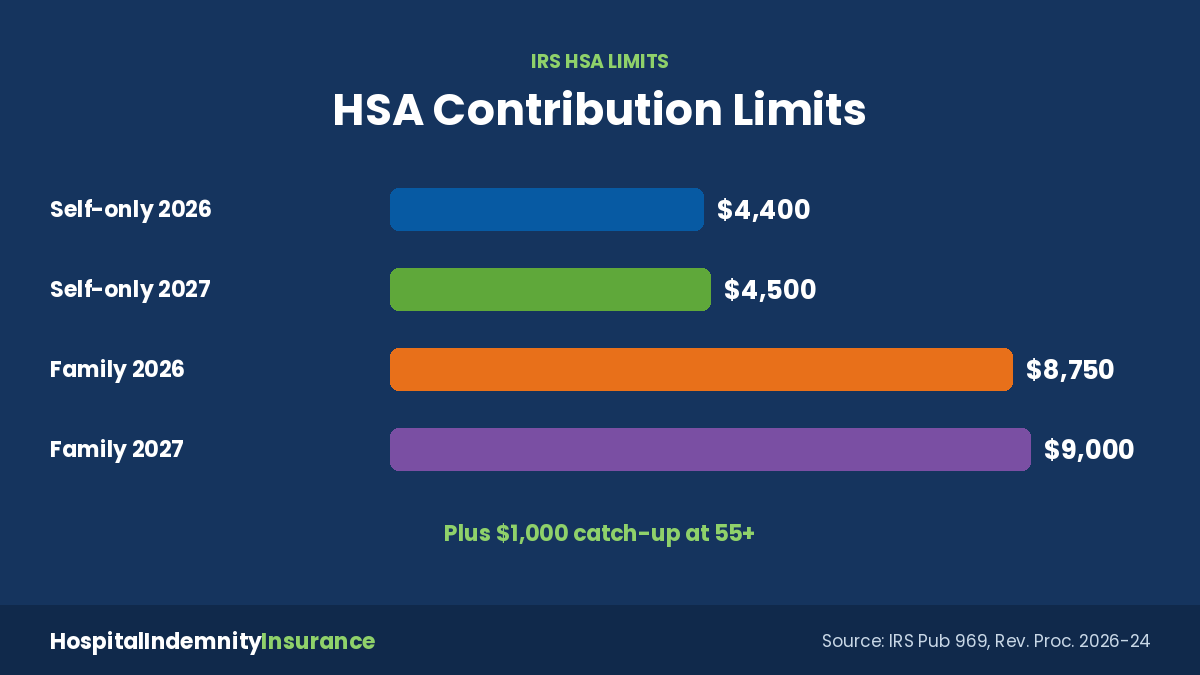
$4,500 / $9,000
2027 HSA contribution limit, self-only / family (IRS Rev. Proc. 2026-24)
$1,750
2027 minimum deductible for an HSA-qualified plan, self-only (IRS)
$1,000
added catch-up contribution allowed at age 55 or older (IRS)
6 months
how far back Part A can start if you apply after 65 (SSA)
An HSA has a strict entry rule: while you contribute, the only health coverage you may hold is a qualifying high-deductible plan plus a short list of exceptions. Hospital indemnity sits on that list, but only when it is built the way the tax code describes.
Below: the exact rule, the benefits that cross the line, four insurers’ HSA-ready designs, and how it fits workers, families, the self-employed and people nearing Medicare. For how the deductible gap works day to day, see hospital indemnity for high-deductible plans.