Reviewed by Russell Noga, Licensed Insurance Agent — Last updated November 8, 2026
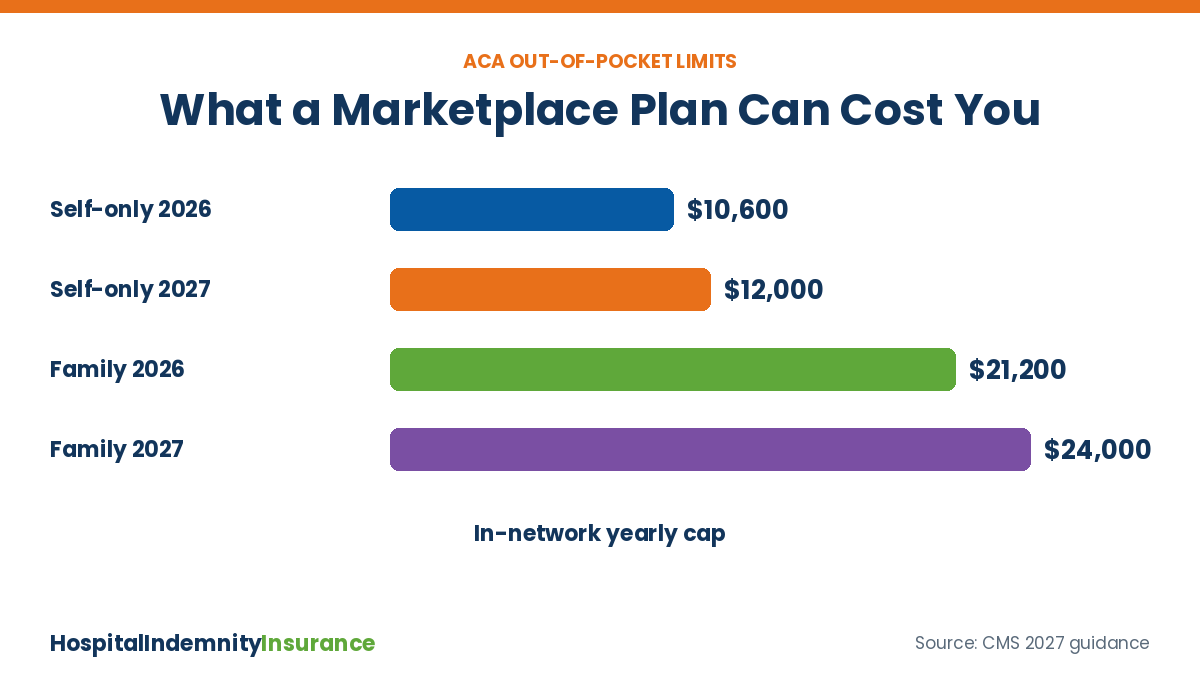
You can buy hospital indemnity insurance with an ACA plan, but you buy it directly from an insurer or licensed agent, not on HealthCare.gov, and you pay its full premium yourself because premium tax credits only apply to the Marketplace health plan. The indemnity policy pays you fixed cash when you are hospitalized, which can help with a 2027 Marketplace out-of-pocket limit as high as $12,000 for one person.
2027 by the Numbers
$12,000
2027 ACA out-of-pocket maximum, self-only, up from $10,600 in 2026 (CMS)
$24,000
2027 ACA out-of-pocket maximum for a family plan (CMS)
$3,786
average 2026 Marketplace deductible, up 37% from 2025 (KFF analysis)
40%
share of 2026 Marketplace plan selections that were bronze, up from 30% (KFF)
An Obamacare plan protects you from the worst medical bills, yet it still expects you to pay the deductible, then coinsurance, up to a yearly cap. In 2027 that cap rises again. A single night in the hospital can use up most of a bronze deductible before anything else happens.
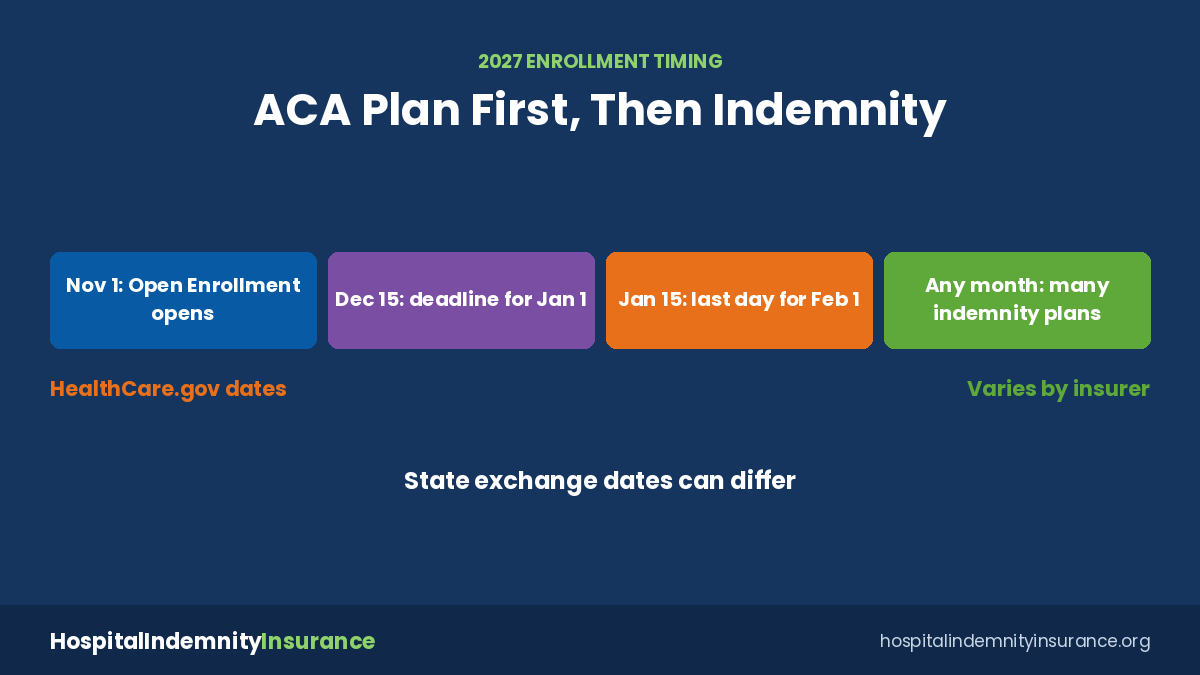
Pairing a Marketplace plan with a hospital indemnity policy is one way to set aside cash for that moment. Below: the 2027 numbers, why the two are bought in different places, what your subsidy won’t pay for, and how timing works. The core contrast is on hospital indemnity vs health insurance.