Speak with a licensed insurance agent

1-888-891-0229

The Hartford Hospital Indemnity Insurance: Benefits, Eligibility and How It Works

Reviewed by Russell Noga, Licensed Insurance Agent — Last updated October 28, 2026

The Hartford hospital indemnity insurance is a group plan, offered mainly through employers, that pays you fixed cash for a covered hospital admission, each day you stay and time in intensive care. Your employer chooses the benefit amounts from The Hartford’s menu, so the details in your own plan summary are what count.

The Hartford is best known for auto, home and business insurance, but it is also one of the large group benefits carriers in the U.S. Its hospital indemnity coverage is written by Hartford Life and Accident Insurance Company, which AM Best rates A+ (Superior). Most people get it as a voluntary benefit at work, paid through payroll deduction.

This guide explains what The Hartford’s plan can include, who can enroll, the rules that affect a payment and how it fits next to your health plan. If you are new to this coverage, start with what is hospital indemnity insurance through an employer.
Compare Hospital Indemnity Plans in Your Area

How The Hartford Hospital Indemnity Insurance Works

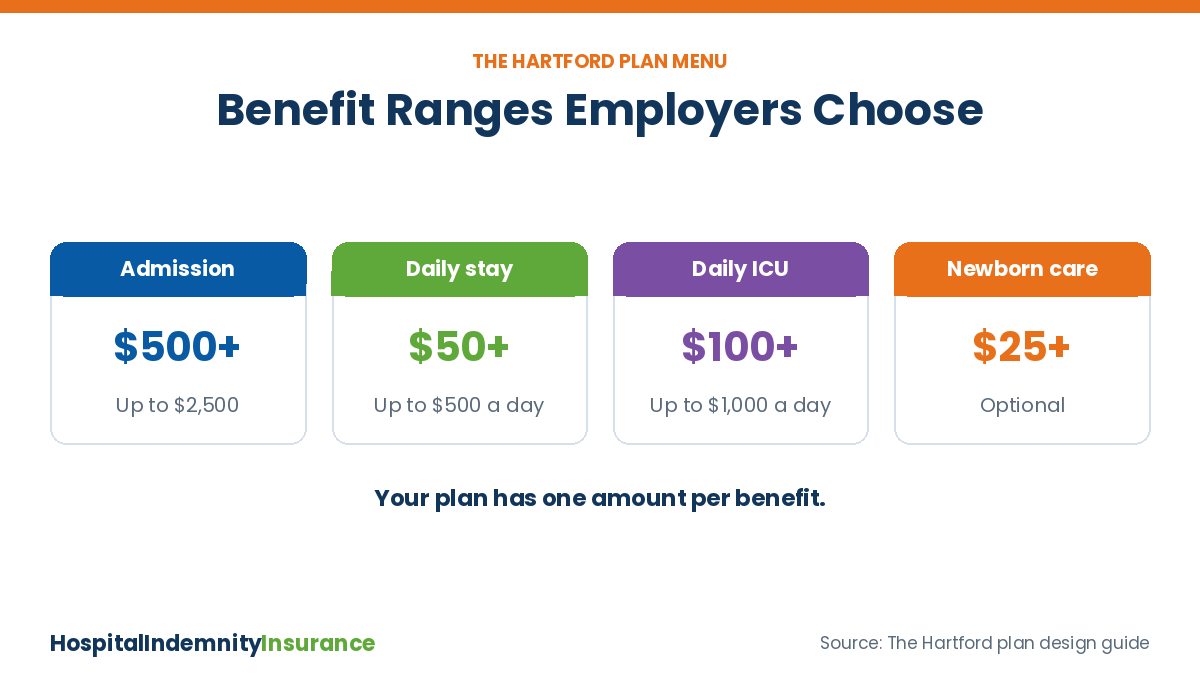
The Hartford hospital indemnity insurance benefit ranges for admission, daily stay and ICU

The Hartford calls this coverage a hospital confinement indemnity policy. When you are admitted to a hospital for a covered reason, it pays set dollar amounts to you, not to the hospital. You can use the money for a deductible, copays, rent, child care or anything else.

Fixed amounts, not bills. The plan pays what your benefit schedule says, no matter what the hospital charges.

Sold through work. Employers offer it as a voluntary benefit. It can be fully employee-paid, fully employer-paid or shared.

Covers the family. Spouses or partners can enroll if the employee is eligible, and children can be covered from birth to age 26.

Important: Hospital indemnity is a limited-benefit plan that pays fixed cash amounts. It is NOT health insurance, does not replace major medical coverage or Medicare and does not meet ACA minimum essential coverage.

Hospital Indemnity Quotes

Call a Licensed Agent Now

Compare hospital indemnity plans from several insurance companies in one call. Any age.

☎ 1-888-891-0229

No obligation to enroll

Benefits The Hartford Plan Can Include

Your employer builds the plan from a menu. The ranges below come from The Hartford’s voluntary hospital indemnity plan design guide. Your own plan will have one amount for each benefit it includes.

Benefit Range employers can choose Typical day limit
First-day hospital admission $500 to $2,500 1 day per stay (up to 5 available)
Daily hospital confinement $50 to $500 a day 90 days standard (10 to 360 available)
Daily ICU $100 to $1,000 a day 30 days standard
First-day ICU (optional) $1,000 to $5,000 1 day standard
Observation / short stay (optional) $25 to $500 a day 1 day standard; larger groups
Newborn routine care (optional) $25 to $500 1 day
Outpatient surgery (optional) $50 to $1,000 Larger groups

Source: The Hartford voluntary hospital indemnity plan design guide. Benefits, amounts and availability vary by employer plan and state.

A hospital stay generally has to last at least 20 hours in a row to count as a confinement, though the rule can vary by state. Nursing homes, rest homes and similar facilities do not count as hospitals.

Here is a simple example. Say your employer’s plan pays a $1,000 first-day admission benefit and $100 a day for confinement. A three-day hospital stay would pay $1,000 plus $300, or $1,300, straight to you. If your plan includes an ICU benefit, a day in intensive care would add that amount too. These numbers are only an illustration; your plan summary shows your real amounts.

Who Can Enroll and When

Because this is a group plan, your job sets most of the eligibility rules. Here is what The Hartford’s guide describes.

Employees. Usually those working at least 30 hours a week at smaller employers or 20 hours at larger ones. Employers can set their own hour rules.

Spouses and partners. Eligible when the employee is eligible.

Children. From birth to age 26.

No health questions. The Hartford offers guaranteed issue to covered people, though rules can vary by state.

Most people can sign up only during their employer’s open enrollment or when they are first hired, or after a qualifying life event. That makes it a good benefit to review each fall, especially if you are planning a pregnancy. See hospital indemnity insurance for pregnancy.

Rules That Affect Your Payment

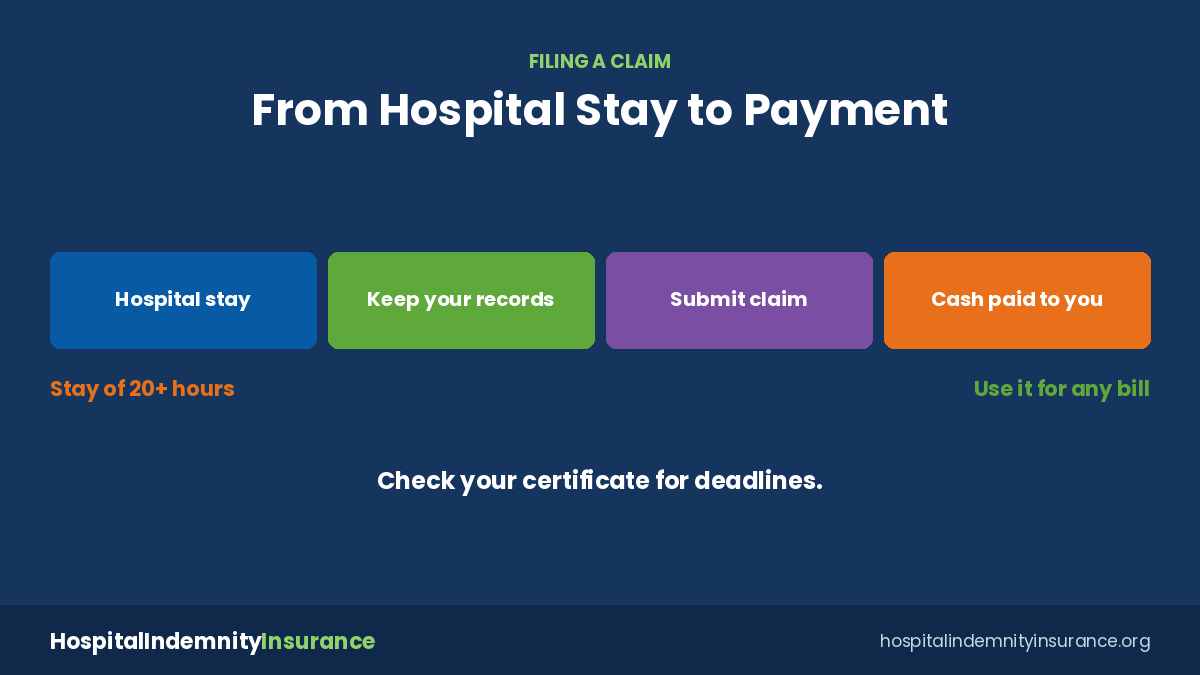
How to file a claim for The Hartford hospital indemnity insurance step by step

Two employers can both offer The Hartford and have quite different rules. Check these items in your plan summary or certificate.

Rule What The Hartford allows What to check
Pre-existing condition limit None, or limits such as 12/12, 6/12, 3/12, 6/6 or 3/6 Which one your employer chose
Illness waiting period Optional 30-day wait Whether it applies to you
Portability Included; some states use continuation instead How to keep coverage if you leave your job
Term age limit Employers can set an age limit from 65 to 85 When your coverage would end

Source: The Hartford voluntary hospital indemnity plan design guide.

Broker tip: A 12/12 pre-existing limit means a condition treated in the 12 months before coverage is not covered until you have been insured 12 months. If you expect a planned surgery or birth soon, find this rule first.

See Individual Hospital Indemnity Plans in Your ZIP Code

Is The Hartford Plan a Good Fit?

Hospital indemnity through work tends to be most useful when your health plan leaves you with a large bill for a hospital stay.

High-deductible health plans. A first-day admission benefit can help cover a deductible of several thousand dollars.

Growing families. Admission and newborn benefits can help with the cost of delivery, if your plan includes them and any pre-existing limit has passed.

Low savings. Cash for bills at home can help if a hospital stay means missed paychecks.

Strong carrier. AM Best affirmed Hartford Life and Accident’s A+ (Superior) rating in July 2026.

If your employer doesn’t offer The Hartford, or you are self-employed or on Medicare, you can buy an individual plan instead. Compare options in our list of hospital indemnity insurance providers.

How to File a Claim With The Hartford

1

Keep your hospital records. Save papers that show your admission and discharge dates and times and any ICU days.

2

Find your plan details. Look up your certificate or plan summary through your employer’s benefits site or The Hartford.

3

Submit the claim. File online or with a claim form and attach the requested records.

4

Check related coverage. If you also have accident or critical illness coverage, a single stay may qualify for more than one claim.

5

Watch the deadline. Your certificate lists how long you have to file. File soon after discharge.

For a general walk-through, read our guide to the claim process for hospital indemnity insurance.

Bottom Line

The Hartford hospital indemnity insurance is a group plan, written by A+ rated Hartford Life and Accident, that pays fixed cash for hospital admissions, daily stays and ICU time. Your employer picks the amounts and rules, so read your plan summary for the pre-existing limit and portability before you enroll or plan a hospital stay.

Get Free Hospital Indemnity Insurance Quotes

The Hartford Hospital Indemnity Insurance — Frequently Asked Questions

➤ Can I buy The Hartford hospital indemnity insurance on my own?

The Hartford’s hospital indemnity plan is offered mainly through employers. If your job doesn’t offer it, you can compare individual hospital indemnity plans from other carriers.

➤ What does The Hartford hospital indemnity pay?

It depends on your employer’s plan. The Hartford’s menu allows first-day admission benefits of $500 to $2,500 and daily benefits of $50 to $500, plus optional ICU, observation and newborn benefits.

➤ Do I have to answer health questions?

The Hartford’s guide says coverage is guaranteed issue for covered people, though rules can vary by state and plan.

➤ Does it cover pre-existing conditions?

That depends on your employer’s choice. Some plans have no limit, while others use a limit such as 12/12 or 6/12.

➤ Can I keep coverage if I leave my job?

The Hartford’s plan includes portability, though some states use continuation instead. Check your certificate for the steps and deadline.

➤ Who can I cover?

Eligible employees, their spouses or partners, and children from birth to age 26.

➤ Is The Hartford a strong insurer?

Yes. AM Best affirmed an A+ (Superior) financial strength rating for Hartford Life and Accident Insurance Company in July 2026.

➤ Is The Hartford hospital indemnity health insurance?

No. It is a limited-benefit plan that pays fixed cash amounts. It does not replace health insurance and does not meet ACA minimum essential coverage.

Hospital Indemnity Quotes

Call a Licensed Agent Now

Compare hospital indemnity plans from several insurance companies in one call. Any age.

☎ 1-888-891-0229

No obligation to enroll

Find & Compare Plans Online

Speak with a licensed insurance agent

1-888-891-0229

ZRN Health & Financial Services, LLC, a Texas limited liability company